Category: Policy

  • SEC Staff Spell Out When Token Voters Aren’t a ‘Central Party’

    SEC Staff Spell Out When Token Voters Aren’t a ‘Central Party’

    Staff at the Securities and Exchange Commission have added three new answers to their crypto FAQ, spelling out when token holders who vote on a network’s decisions count as the kind of “central party” that can keep a token in securities territory.

    The update, dated Nov. 2, comes from the SEC’s Division of Corporation Finance. It adds questions 1.4, 1.5 and 1.6 to the FAQ the division first published on Sept. 25 and revised on Sept. 28. The answers explain how shared governance fits the SEC’s March 17 interpretive release, which says digital commodities are not themselves securities and describes a “functional crypto system” as one with no central party overseeing participation or handing out rewards.

    Voting alone isn’t control. The release defines a central party as a person, entity or group with operational, economic or voting control of a crypto system. Answer 1.4 calls this a facts-and-circumstances question, but says people who take part in a network’s broad-based governance generally will not be treated as a “group” if they are not affiliated and have no agreement, arrangement or understanding, formal or informal, to act together outside the governance system itself. That includes coordinating through delegated votes. The staff says the same applies when governance sits inside a foundation or association and participation depends on holding the network’s native token. Even if voters did form a group, they would still need actual control to count as a central party.

    What oversight looks like. Answer 1.5 lists the powers that do mark a central party: unilateral authority to grant or limit access, change voting processes for upgrades or token distributions, decide who can validate transactions, modify the network’s code, reverse transactions, or revoke access. A system generally has no such overseer when every material part of its operation runs automatically on rules-based code, or when any remaining discretion is exercised only through broad-based governance.

    Working is not the same as decentralized. Answer 1.6 separates the two ideas. A functional system lets its native token do what it was programmed to do. A decentralized system runs without any person or group holding operational, economic or voting control. The staff says the degree of decentralization can vary.

    The limits. These are staff views, not a Commission rule. The FAQ says the answers have no legal force or effect, do not change the law and create no new obligations, and the Commission has neither approved nor disapproved them. The staff also limits the “group” answer to the digital-commodity question; it does not carry over to other parts of securities law, such as the definition of an exchange.

    For projects that run on token votes, including DAOs and foundation-led networks, the practical test is now clearer: who can actually change the rules, stop users, or undo transactions, alone or together.

    What to watch: whether the Commission itself adopts any of this, including in its Regulation Crypto Assets proposal from August, which the FAQ already cites, and how projects with foundations or heavy vote delegation describe their own control in filings.

    Sources: SEC, Cryptonews.
  • Ripple Gets Final OCC Approval for a National Trust Bank. Here’s What It Can and Can’t Do

    Ripple Gets Final OCC Approval for a National Trust Bank. Here’s What It Can and Can’t Do

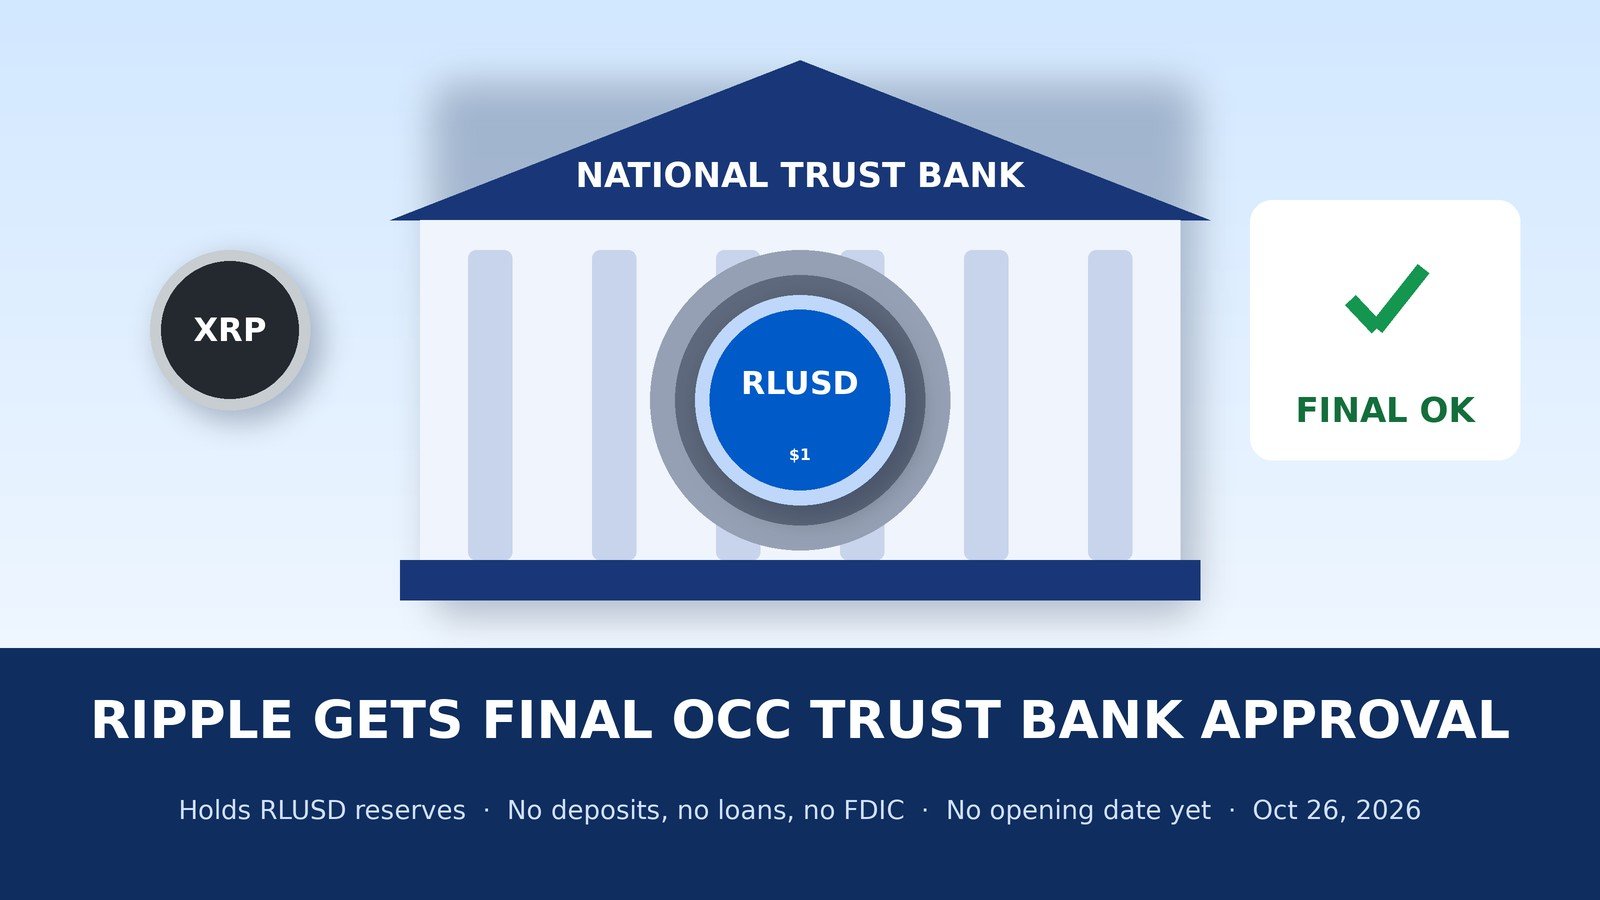
    The Office of the Comptroller of the Currency (OCC) has given final approval to Ripple National Trust Bank, a federally chartered national trust bank that will manage the reserves behind Ripple’s dollar stablecoin, RLUSD. Ripple announced the approval on Monday, Oct. 26, the evening before its Swell conference opens in New York (Oct. 27–29).

    Ripple applied in July 2025 and received conditional approval on Dec. 12, 2025. Monday’s decision moves the charter from conditional to final.

    What the trust bank is approved to do

    • Manage RLUSD’s segregated reserve assets.
    • Act as collateral trustee on behalf of RLUSD holders.
    • Provide fiduciary digital asset custody for enterprise clients.

    RLUSD itself will still be issued by Standard Custody & Trust Company, Ripple’s trust company regulated by the New York Department of Financial Services. Ripple says that puts RLUSD under both state and federal oversight. Ripple puts RLUSD’s market value at about $2.5 billion; CoinGecko showed about $2.6 billion on Tuesday morning. BNY is the primary custodian of RLUSD’s reserves, and Ripple publishes monthly attestations.

    “For years, we’ve said crypto and banks work better together. Final approval for Ripple National Trust Bank is what that looks like in practice,” CEO Brad Garlinghouse said.

    What it is not

    A national trust bank is not a commercial bank. Trust banks of this kind do not take deposits or make loans, and they do not carry FDIC deposit insurance. Ripple’s release describes what the bank will do “once open” and gives no opening date.

    The approval does not involve any purchase or sale of XRP. RLUSD is a dollar-backed stablecoin. XRP traded near $1.30 Tuesday morning, up less than 1% over 24 hours, per CoinGecko.

    Where it fits

    Circle received final OCC approval for its national trust bank in July. Coinbase holds a preliminary approval from April, and Crypto.com and Bridge received conditional approvals in February.

    The same day, the OCC separately urged community banks to consider applying, directly or through a subsidiary, to become permitted payment stablecoin issuers under the GENIUS Act. The OCC’s final GENIUS Act rule takes effect Jan. 18, 2027; applications open after the paperwork is cleared by the Office of Management and Budget.

    The charter program faces a court challenge. On Oct. 2, the Independent Community Bankers of America (ICBA) sued the OCC in federal court in Washington, D.C., challenging the agency’s March 2026 chartering rule, a related interpretive letter, and one firm’s conditional trust bank approval. The ICBA argues that uninsured trust banks give crypto firms “a side door into the banking system.” The case is pending.

    What to watch

    • An opening date for Ripple National Trust Bank.
    • Any RLUSD or bank-related announcements at Swell this week.
    • Rulings in the ICBA case against the OCC.
    • Final decisions on the remaining conditional charters.

    Sources: Ripple, Business Wire, Office of the Comptroller of the Currency, CoinDesk, Decrypt, The Block, Cointelegraph, PYMNTS, CoinGecko.

  • Bank of Israel Says Crypto Cannot Be Used to Get Around Sanctions

    Bank of Israel Says Crypto Cannot Be Used to Get Around Sanctions

    The Bank of Israel said Saturday that cryptocurrencies “cannot serve as a means to circumvent sanctions,” a day after Prime Minister Benjamin Netanyahu said he had asked for a plan involving blockchain to prepare for possible sanctions, including banking sanctions.

    The statement, quoted in translation from Hebrew by Globes, the Times of Israel and Ynet, went on: “The right course for the Israeli economy is to maintain economic relations with our primary trading partners and to focus on preventing sanctions and their negative impact on the economy. This is the responsibility of the political leadership, and it should act upon it.” The Times of Israel rendered the opening line as crypto “cannot be used as a route for bypassing sanctions.”

    As of Saturday afternoon ET, the statement did not appear on the press release page of the bank’s English-language website.

    Netanyahu made the remarks in an interview with Roy Katz broadcast Friday, Oct. 23, on Channel 10, Israel’s economic news channel. “We need to understand that there could be sanctions, including banking sanctions. You need to prepare an economy that can bypass them,” he said, according to a translation by The Block. “I’m working on that too.” Asked whether blockchain was the alternative, he answered, “One of them, certainly. And I have already requested that a plan for this should be prepared,” in Globes’ translation.

    He did not say which countries might impose such sanctions, who would draw up the plan, which networks or currencies it might use, or when. Ynet reported that officials in Israel’s economic ministries and the Prime Minister’s Office said they knew of no such plan. A senior economic official told Channel 12 that “the idea will certainly not achieve its goal. Even talking about it could harm the economy,” the Times of Israel reported. Separately, 109 senior economists, business executives and former public officials, writing as the Economists’ Forum, said in a joint statement that they felt “grave concern and anxiety” over the remarks, the Times of Israel reported.

    The remarks followed sanctions announced by Britain and 11 other Western countries on goods from Israeli settlements in the West Bank, the Times of Israel reported. Israelis vote in a general election on Oct. 27.

    Speaking to Channel 14 on Saturday evening, Netanyahu did not withdraw the idea. “We have other means; crypto is one of them — it is not the sole method, and it is not certain that it will actually be used,” he said, according to Globes. “I thank the Bank of Israel for their advice, but I do what I think is right.”

    Sources: Globes, The Times of Israel, Ynet, The Times of Israel (Economists’ Forum), The Block

  • Malaysia and Thailand Join Singapore’s BLOOM Project for Cross-Border Stablecoin and Tokenized-Deposit Settlement

    Malaysia and Thailand Join Singapore’s BLOOM Project for Cross-Border Stablecoin and Tokenized-Deposit Settlement

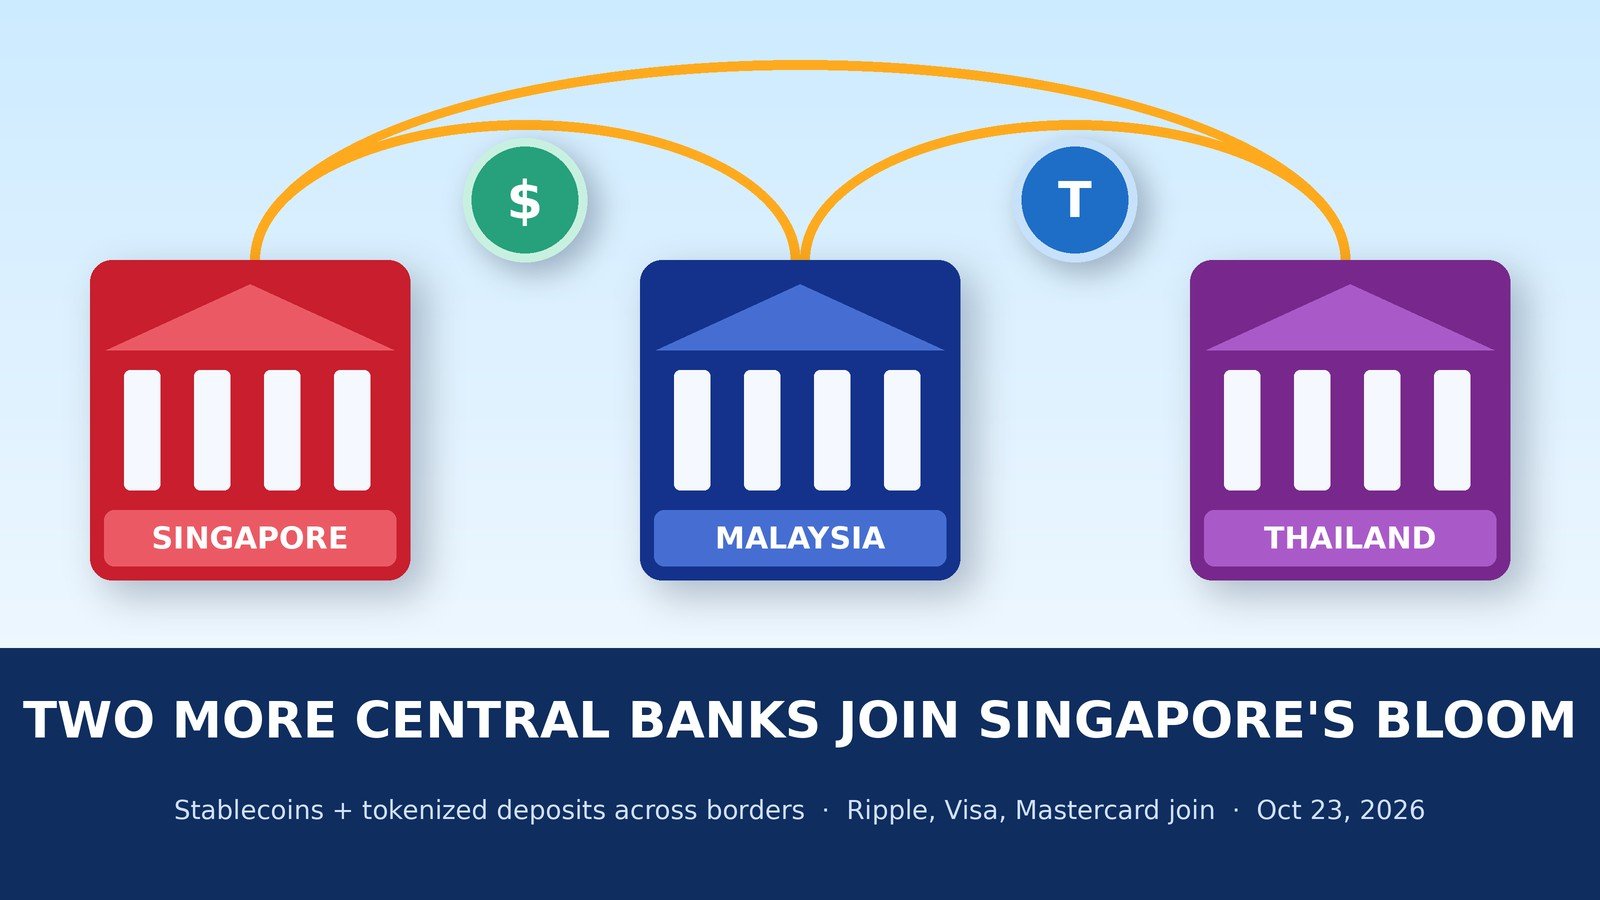
    Singapore’s central bank says two of its neighbors are now inside its project to move money across borders with stablecoins and tokenized bank deposits.

    The Monetary Authority of Singapore (MAS) announced on Oct. 23 that Bank Negara Malaysia and the Bank of Thailand have joined BLOOM as “policymaker members.” BLOOM stands for Borderless, Liquid, Open, Online, Multi-currency.

    MAS also named nine new industry participants: Airwallex, Mastercard, Maybank, Monee, Nium, Ripple, ShopeePay, Visa and the World Bank Group. They join a list that already included Anchorage Digital, Ant International, Circle, Coinbase, DBS, J.P. Morgan, Kasikornbank, OCBC, Partior, Schroders, Standard Chartered, StraitsX, Stripe, Temasek, UOB and Xweave.

    What BLOOM is trying to fix

    Banks that want to pay each other in digital money across borders today often need a separate deal with each partner and each market. MAS says BLOOM aims to build shared frameworks so they don’t have to, which it says should cut costs and speed up launches.

    The settlement assets in view are tokenized commercial bank money and stablecoins “that meet regulatory expectations,” according to MAS. The project builds on Project Orchid, Singapore’s earlier work on a digital Singapore dollar.

    MAS listed three work areas:

    • Acceptance and settlement: how banks accept different forms of digital money in cross-border deals, how counterparties contract, and how trades finally settle.
    • Interoperability: how separate digital money systems can work across networks and borders.
    • Programmable controls: safeguards such as identity checks, sanctions screening and transaction controls built into the payment itself.

    What the central banks said

    “The future of finance will involve multiple forms of digital money operating across different institutions and markets,” said Leong Sing Chiong, MAS deputy managing director for markets and development.

    Bank Negara Malaysia Deputy Governor Aznan bin Abdul Aziz said frictionless cross-border payments using multiple digital monies are “now closer to a tangible reality than a far-fetched fantasy.”

    Bank of Thailand Deputy Governor Daranee Saeju said the work would help inform “forward-looking regulatory approaches for tokenised money, particularly in cross-border payments and wholesale settlement,” while keeping oversight “prudent, proportionate, and responsive to evolving risks.”

    What it is not

    This is a coordination project, not a product launch. The MAS release does not name a go-live date, a single token or a single blockchain. Central bank membership means the three regulators will shape the rules as the frameworks are written. It does not mean any of them has approved a specific stablecoin for cross-border use.

    For XRP Ledger watchers, Ripple’s name on the list is the hook. The Block reported that Ripple has said its BLOOM work involves testing trade payments with its RLUSD stablecoin on the XRP Ledger. MAS’s release does not single out any network.

    MAS did not publish expected volumes or a timeline for live cross-border transactions.

    Sources: Monetary Authority of Singapore (media release and BLOOM page, Oct. 23, 2026); The Block; The Business Times.

  • Coldcard Maker Coinkite Faces Proposed Class Action Over Seed-Generation Flaw

    Coldcard Maker Coinkite Faces Proposed Class Action Over Seed-Generation Flaw

    Coinkite Inc., the Toronto maker of Coldcard bitcoin hardware wallets, and co-founders Rodolfo Novak and Peter D. Gray have been named in a proposed class action in the Ontario Superior Court of Justice. The statement of claim was issued Sept. 11 and surfaced this week on the Canadian Bar Association’s class action database, which lists the case as not certified. The allegations are unproven.

    The plaintiff is Amir Reza Naderi of Los Angeles, represented by Foreman & Company of London, Ontario. He says he bought a Coldcard Mk3 in 2022. According to the claim, 1.22940052 BTC, worth about $79,764, was taken from his wallet without authorization on Aug. 6.

    The suit alleges that since about March 2021, Coldcards generated recovery phrases with MicroPython’s Yasmarang software generator instead of the hardware random number generator Coinkite advertised. The claim says the generator relied on predictable inputs such as the device serial number, which left the phrases open to reconstruction.

    Coinkite’s July 30 advisory describes the same mechanism as a “build and link integration error.” It covers two groups of seeds. The first is seeds made on Mk2 and Mk3 firmware 4.0.1 through 4.1.9. The second is seeds made on Mk4, Mk5 and Q models before firmware 5.6.0 or 1.5.0Q. Coinkite estimates effective entropy fell to about 40 bits on older models and 72 bits on newer ones, against a 128-bit target. It says attackers regenerated seeds offline and the devices were not hacked. Fixed firmware is available, but the company says updating “does not change or repair an existing seed,” so affected owners must move to a new seed.

    The claim says thefts began on or about July 30 and puts class losses above $140 million. That figure is the plaintiff’s, and the filing does not explain how it was calculated. Galaxy Research, which tracks the thefts on-chain, attributed 1,789.28 BTC to the exploit with high confidence as of Aug. 24. That was about $114.7 million when taken.

    The suit also alleges that bitcoin engineer James O’Beirne warned Coinkite of “the Defect and other flaws” in May 2025. He has not commented publicly. On July 30, Coinkite wrote: “We were unaware of the bug until today.”

    Naderi seeks certification, damages under Ontario consumer-protection and sale-of-goods law, negligence and contract damages, and punitive damages. The claim names no total dollar figure. It also challenges the arbitration and class-proceeding limits in Coinkite’s terms of sale.

    Coinkite told Bitcoin.com News it “can’t comment on pending litigation” and expects to publish a full postmortem within days. As of Friday morning, its Coldcard security page still said a detailed technical postmortem “remains in preparation.” Hardwire found no statement of defence in the public record.

    Sources: Ontario Superior Court of Justice (statement of claim, via the Canadian Bar Association class action database); Coinkite; Galaxy Research; Bitcoin.com News

  • U.S. Bank Regulator Finalizes First Stablecoin Rulebook: Two-Day Redemptions, No Automatic Freeze, Rewards Judged Case by Case

    U.S. Bank Regulator Finalizes First Stablecoin Rulebook: Two-Day Redemptions, No Automatic Freeze, Rewards Judged Case by Case

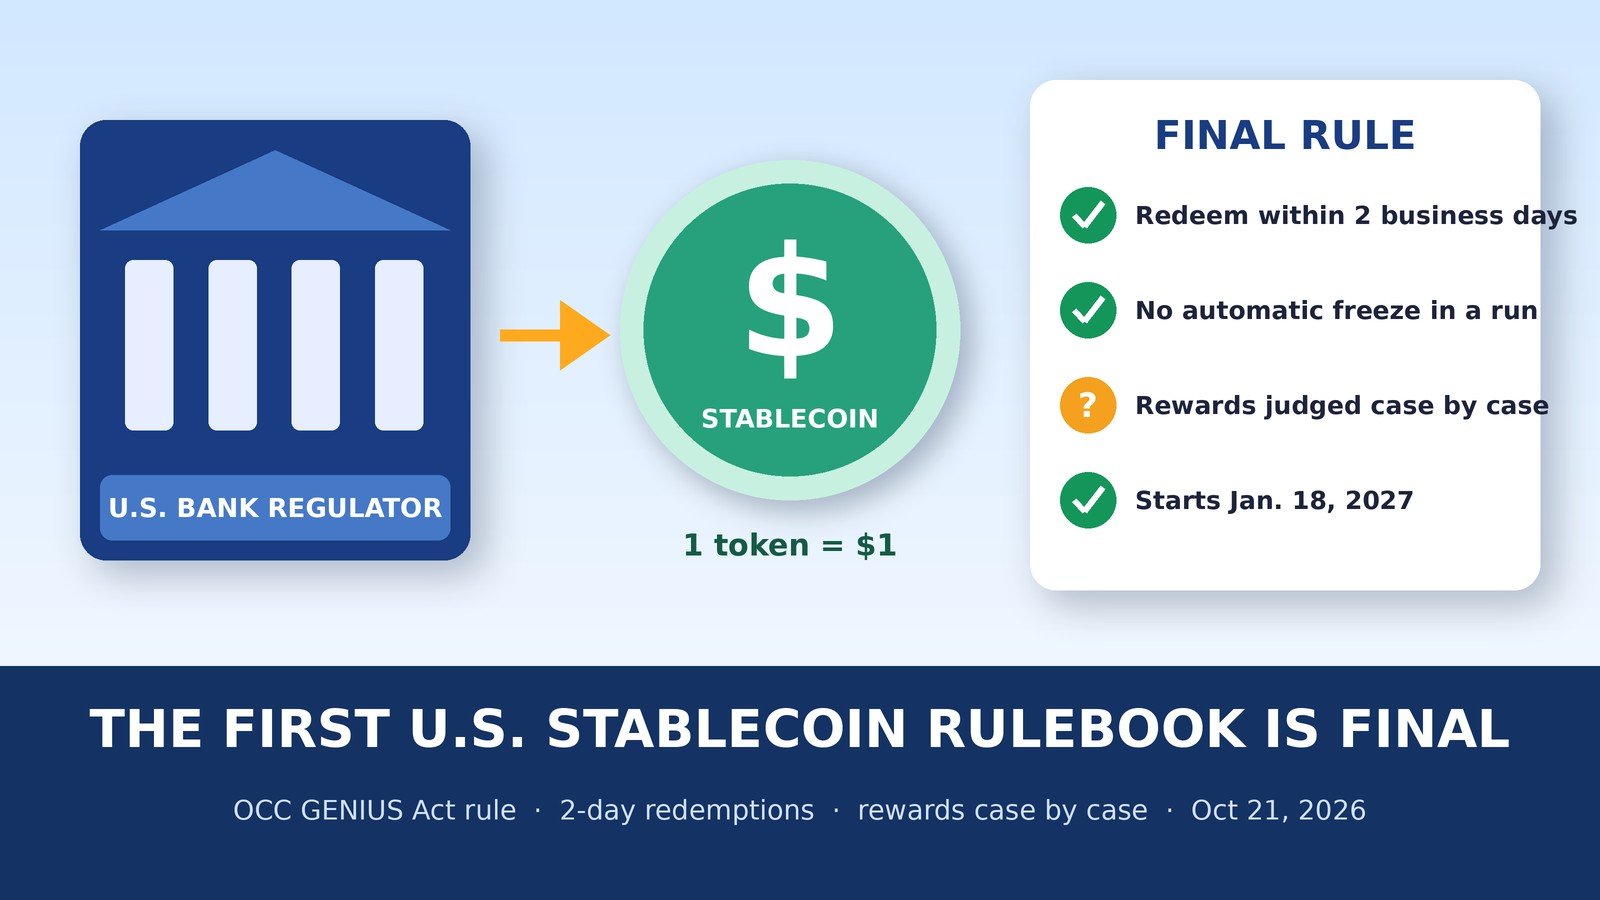
    The first U.S. rulebook for stablecoin issuers is final. On Wednesday, Oct. 21, the Office of the Comptroller of the Currency (OCC), which regulates national banks and federal trust banks, issued its final rule putting the GENIUS Act into practice. The rule and the law both take effect on Jan. 18, 2027. CoinDesk reported that the OCC is the first federal agency to finish its GENIUS Act rules. Other regulators are still writing theirs.

    The rule covers stablecoin issuers that fall under the OCC: subsidiaries of national banks and federal savings associations, federally chartered issuers, certain state-qualified nonbank issuers, and foreign issuers. It also covers some crypto custody done by OCC-supervised firms. Anti-money-laundering and sanctions rules are not in this package. The OCC said those will come in a separate rule written with the Treasury Department.

    What changed from the draft

    The OCC first proposed the rule on March 2, 2026, and received about 328 comments. The final version changes three things that matter to users.

    1. Stablecoin rewards will be judged case by case. The GENIUS Act bans issuers from paying interest or yield to holders “solely in connection with” holding, using or keeping a stablecoin. The draft would have presumed that certain payments through affiliates and related third parties broke that ban unless the issuer proved otherwise. The final rule drops that presumption. The OCC said it will “apply the language of the statute to the facts and circumstances” of each arrangement. It also declined to give a list of allowed or banned setups, declined a small-payments exemption, and said rewards programs that existed before the law “will be evaluated the same” as new ones. The OCC said it keeps its power to act against arrangements that try to evade the ban.

    2. No automatic redemption freeze. Issuers must pay out redemptions within two business days. The draft would have stretched that to seven calendar days automatically if holders asked to redeem more than 10% of a stablecoin’s supply in 24 hours. The OCC removed that, saying an automatic extension “could prove pro-cyclical and trigger or exacerbate runs.” Instead, an issuer that crosses the 10% line must notify the OCC within 24 hours and may ask for more time. The OCC said it expects such extensions to be “rare.”

    3. A smaller cash buffer. The draft required issuers to keep at least 10% of reserves as cash on demand, in bank deposits or at the Federal Reserve. The final rule lowers that to 5%, pointing to new stress-testing and liquidity planning requirements.

    What it means

    For banks, this is the operating manual for issuing a regulated dollar stablecoin under federal supervision. The OCC said it will announce separately when it starts taking applications. Under the law, firms with a pending application when the law takes effect can ask for a waiver of up to 12 months.

    For crypto users, the open question is rewards. Exchanges that pay customers for holding stablecoins get no safe harbor. Whether a given program passes will depend on how the OCC reads the word “solely,” one case at a time. CoinDesk noted the agency signaled that a reward paid “at least in part” for other reasons may fall outside the ban.

    The stakes are growing. Stablecoin transfers reached about $891 billion in the third quarter, according to a Coinbase and The Block study published this week.

    Treasury Secretary Scott Bessent called the GENIUS Act “a watershed moment in American finance.” Comptroller Jonathan Gould said the rule sets “strong standards for reserve backing, redemption, and risk management.”

    A practical note: nothing changes for stablecoin holders today. The rules apply from Jan. 18, 2027.

    Sources: Office of the Comptroller of the Currency (news release); OCC final rule; CoinDesk; The Block

  • France’s Stablecoin-Swap Tax Passed by One Vote. It Isn’t Law, and LCP Says Tuesday’s Budget Vote Will Slip

    France’s Stablecoin-Swap Tax Passed by One Vote. It Isn’t Law, and LCP Says Tuesday’s Budget Vote Will Slip

    France’s National Assembly voted on Friday, Oct. 16, to make swapping crypto into euro- or dollar-pegged stablecoins a taxable event starting Jan. 1, 2027. The margin was one vote, and the measure is still a long way from becoming law.

    Amendment I-3898 to the 2027 finance bill, tabled by Nicolas Sansu of the Democratic and Republican Left group, passed 38 to 37 with 25 abstentions, according to the Assembly’s record of public vote no. 8836. One hundred of the chamber’s 577 deputies took part.

    What the amendment does

    Under current French rules, trading one crypto-asset for another doesn’t trigger tax. The bill comes due when a holder sells for euros or spends. The amendment removes that deferral for swaps that end in “e-money tokens” as defined by the EU’s MiCA regulation, the category that covers single-currency stablecoins such as USDC and EURC. Those gains would fall under France’s existing flat tax on crypto gains. The amendment itself sets no rate; French outlets including Journal du Coin put that tax at 31.4%. The text also changes how gains are counted, using the cost of the specific assets sold rather than France’s current whole-portfolio formula.

    The government opposed it

    Public accounts minister David Amiel asked deputies to withdraw the amendment, telling them that “as things stand, implementing this measure would be too complex,” according to the official record of the sitting. He said stablecoins would first need a clear definition and the tax administration would need a way to trace reallocations inside a portfolio. The finance committee had adopted the measure, although its rapporteur général, Philippe Juvin, said on the floor that he personally considers the current deferral justified given crypto’s volatility.

    What happens next

    The timeline is less settled than several reports suggest. The Assembly’s official agenda, last set by its Conference of Presidents on Oct. 13, still lists a solemn vote on the revenue half of the budget for Tuesday afternoon. But LCP, the Assembly’s own broadcaster, reported Monday that 2,828 of the 3,396 amendments filed remain to be debated and that the vote can’t take place as planned. According to LCP, deputies will resume the revenue section after the social-security budget debate. LCP added that, with no majority in the chamber, the revenue section is more than likely to be rejected. Either way, the bill then goes to the Senate, which can strip the amendment, and a government using Article 49.3 can choose which amendments to keep.

    Hardwire’s Easton argued last week, before the floor vote, that it would tax people for using the very stablecoins Europe’s rules steer them toward.

    What it means for holders

    For holders in France, nothing changes before 2027, and the measure may not survive the process. The amendment names no specific tokens. Several French outlets say it would not reach USDT, which is not authorized under MiCA, but tax authorities have not issued guidance.

    This is a news report on proposed legislation, not tax advice.

    Sources: Assemblée nationale (vote record); Assemblée nationale (amendment I-3898); Assemblée nationale (transcript); LCP; Journal du Coin

  • EU Names USDC Its First ‘Significant’ Stablecoin. Oversight of Its Reserves Moves to the EBA Nov. 12

    EU Names USDC Its First ‘Significant’ Stablecoin. Oversight of Its Reserves Moves to the EBA Nov. 12

    The European Banking Authority has classified USDC, the dollar stablecoin issued in the EU by Circle Internet Financial Europe SAS, as a “significant” e-money token under the bloc’s Markets in Crypto-Assets rules, known as MiCA.

    It is the first token to get that label. In its Oct. 14 announcement, the Paris-based authority said 45 e-money tokens have been notified in the EU under MiCA, and USDC is the first of them to be classified as significant. E-money tokens are stablecoins that track a single official currency.

    Who watches what

    The label splits supervision in two. From Nov. 12, direct oversight of USDC’s own funds, reserve of assets, liquidity requirements, and recovery and redemption plans moves from France’s Autorité de Contrôle Prudentiel et de Résolution (ACPR) to the EBA. The ACPR keeps areas including governance, qualifying holdings, fit-and-proper checks, outsourcing and conflicts of interest. The two authorities said they will work together on the handover.

    In plain terms: the parts of the token that decide whether a holder gets a dollar back, the reserves and the plan for paying people out, now sit with an EU-level supervisor instead of a single national one.

    USDC is issued in the United States by a separate company, Circle Internet Financial, LLC. To cover that cross-border setup, the EBA said it has signed a memorandum of understanding with the New York State Department of Financial Services on cooperation and information sharing.

    What the EBA did not say

    The EBA did not say which of MiCA’s significance tests USDC met. The rules look at measures such as the number of holders, the value of tokens issued, and the number and value of transactions, and a 2024 Commission regulation sets out how they are counted. The EBA reviews each classification every year. Under MiCA, an issuer of a significant e-money token also faces extra requirements, mainly on liquidity and own funds, which the EBA will supervise.

    USDC has about $73 billion in circulation worldwide, according to The Block’s data. Circle had not published a statement on the classification as of Thursday morning.

    A busy week for EU stablecoin rules

    The decision caps a week of moves by EU regulators. On Oct. 8, the European Securities and Markets Authority said crypto firms licensed under MiCA should stop offering services involving stablecoins that do not comply with MiCA, and asked national supervisors to have existing exposures cleaned up within three months. On Wednesday, as Hardwire reported, Qivalis, a euro stablecoin company backed by 37 European banks, received its e-money license from the Dutch central bank. That token has not launched.

    The bottom line: the EU’s biggest regulated dollar stablecoin now gets a second, EU-level supervisor for its reserves and redemption plans, starting Nov. 12.

    Sources: European Banking Authority; European Securities and Markets Authority; The Block; Cointelegraph; Hardwire Crypto

  • Euro Stablecoin Backed by 37 European Banks Gets Dutch E-Money License. The Token Isn’t Out Yet

    Euro Stablecoin Backed by 37 European Banks Gets Dutch E-Money License. The Token Isn’t Out Yet

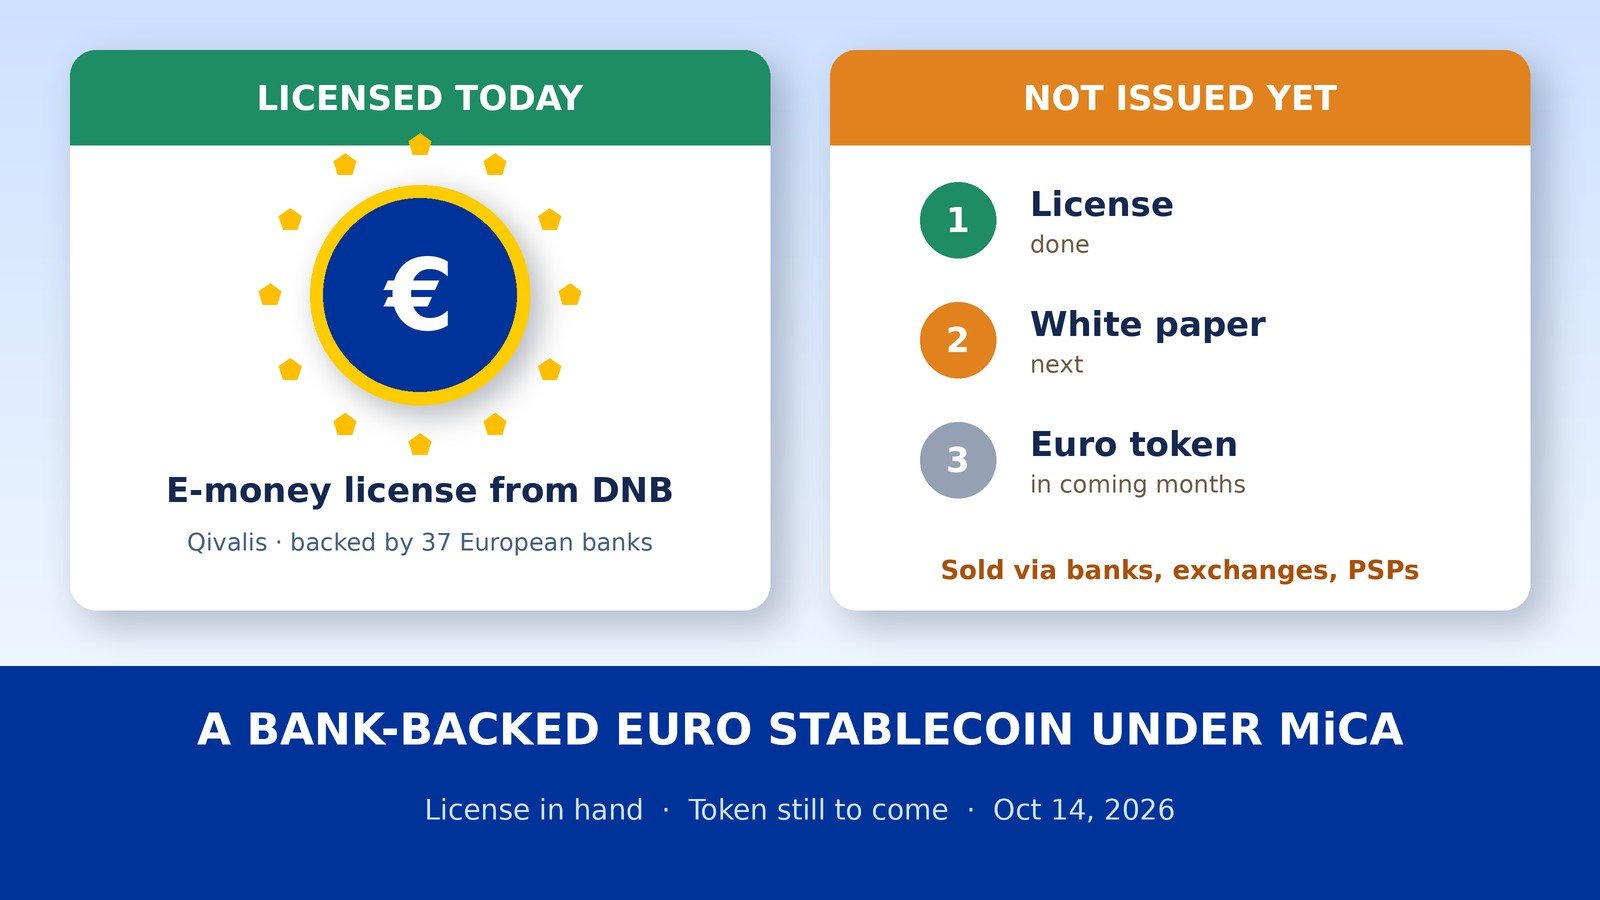
    Qivalis, the Amsterdam company backed by 37 European banks to issue a euro stablecoin, said on Oct. 14 that the Dutch central bank, De Nederlandsche Bank (DNB), has authorised it as an electronic money institution. That puts the company under DNB’s ongoing supervision and makes it eligible to issue euro-denominated electronic money tokens, the regulated form of stablecoin under the EU’s Markets in Crypto-Assets rules, known as MiCA.

    The token itself is not out yet. Qivalis says issuance is planned “within the next months” and will still be subject to MiCA’s requirements, including publication of a white paper. It did not give a date.

    What the license does

    Under MiCA, an e-money token is pegged to a single official currency and must be issued by a licensed bank or e-money institution. Holders have a legal claim on the issuer and can redeem at face value at any time, CoinDesk noted. The tokens cannot pay interest.

    Qivalis called the authorisation “a decisive regulatory condition” for issuing its token. “Europe’s currency deserves Europe’s rules – on-chain,” said Jan-Oliver Sell, the company’s chief executive. “We believe Europe should have a euro-denominated on-chain settlement asset issued under European law and subject to European regulatory standards.”

    Who it is for

    Qivalis will not sell directly to the public. It plans what it calls a B2B2X model, distributing the token through banks, exchanges, payment providers and market infrastructure firms. The backers span 15 countries and include BBVA, BNP Paribas, ING and DZ Bank, according to CoinDesk, which also reported that Fireblocks was picked to provide the digital asset infrastructure. The supervisory board is chaired by Sir Howard Davies, a former chairman of NatWest Group and of the UK’s old Financial Services Authority.

    What Qivalis has not said yet: which member banks will use the token first, how much money they expect to move with it, and which blockchains it will run on.

    The U.S. banks are on a slower clock

    The license lands a day after Wells Fargo’s third-quarter call. Chief executive Charlie Scharf said there that Wells Fargo and 20 other international financial institutions are setting up a company to issue stablecoins “beginning in the first half of 2027.” He also said the bank launched tokenized deposits on its own blockchain platform last month for corporate and commercial clients. Chief financial officer Mike Santomassimo said that service is “in production,” at “small volume so far,” with payments reaching the beneficiary “in two minutes or less.”

    The bottom line: a 37-bank euro stablecoin now has its license in hand. The token, its white paper and its first users are still to come.

    Sources: Qivalis; CoinDesk; Wells Fargo Q3 2026 earnings call; crypto.news

  • Treasury Formally Drops Crypto Mixer and Self-Custody Wallet Reporting Proposals

    Treasury Formally Drops Crypto Mixer and Self-Custody Wallet Reporting Proposals

    The Treasury Department’s Financial Crimes Enforcement Network formally withdrew two long-pending crypto proposals on Tuesday. The proposals would have required banks and money services businesses to collect and report more data on transactions tied to foreign crypto mixers and self-custodied wallets.

    Both withdrawal notices were published in the Federal Register on Oct. 6 after going on public inspection Monday. Both are signed by FinCEN Deputy Director Jimmy L. Kirby.

    The first withdraws FinCEN’s October 2023 finding, made under Section 311 of the USA PATRIOT Act, that international crypto mixing is “a class of transactions of primary money laundering concern,” along with the proposed rule attached to it. That rule would have required covered institutions to report mixing-linked transactions with details including wallet addresses, transaction hashes and IP addresses.

    The second pulls a December 2020 proposal on “unhosted wallets.” It would have required banks and money services businesses to verify customers and keep records when a counterparty used a self-hosted wallet for transactions above $3,000, and to file reports above $10,000. “FinCEN will take no further action on this NPRM,” the notice says. Treasury’s regulatory agenda had already listed that proposal as withdrawn in 2024, Unchained reported; Tuesday’s notice makes it official.

    Both notices cite the July 2025 report of the President’s Working Group on Digital Asset Markets. The mixer notice quotes the report’s line that the administration “supports the ability of lawful users of digital assets to privately transact on a public blockchain.” It also says commenters warned the broad definition of mixing “could have a chilling effect on legitimate activity and place a large reporting burden on covered financial institutions.”

    What the notices don’t do matters as much. Neither proposal ever took effect, so current Bank Secrecy Act requirements stay as they are, and there is no new safe harbor for mixers. FinCEN said it “will continue to monitor activity involving CVC mixers” for illicit finance and “may take appropriate steps in the future.” Sanctions run on a separate track: on Oct. 2, Treasury’s Office of Foreign Assets Control designated a Hamas financing network that Treasury said moved money partly through crypto.

    Coin Center, the policy group that filed comments against both proposals, called the move “a significant victory for financial privacy,” Unchained reported, citing a post by Coin Center’s Jason Somensatto.

    For compliance teams, the practical change is smaller than the headlines suggest. A proposed reporting burden that had sat idle for years is now off the table, and the existing rulebook stays as written.

    Sources: Federal Register mixer withdrawal (2026-20429); Federal Register unhosted-wallet withdrawal (2026-20430); Treasury OFAC press release (Oct. 2); The Block; Unchained.