
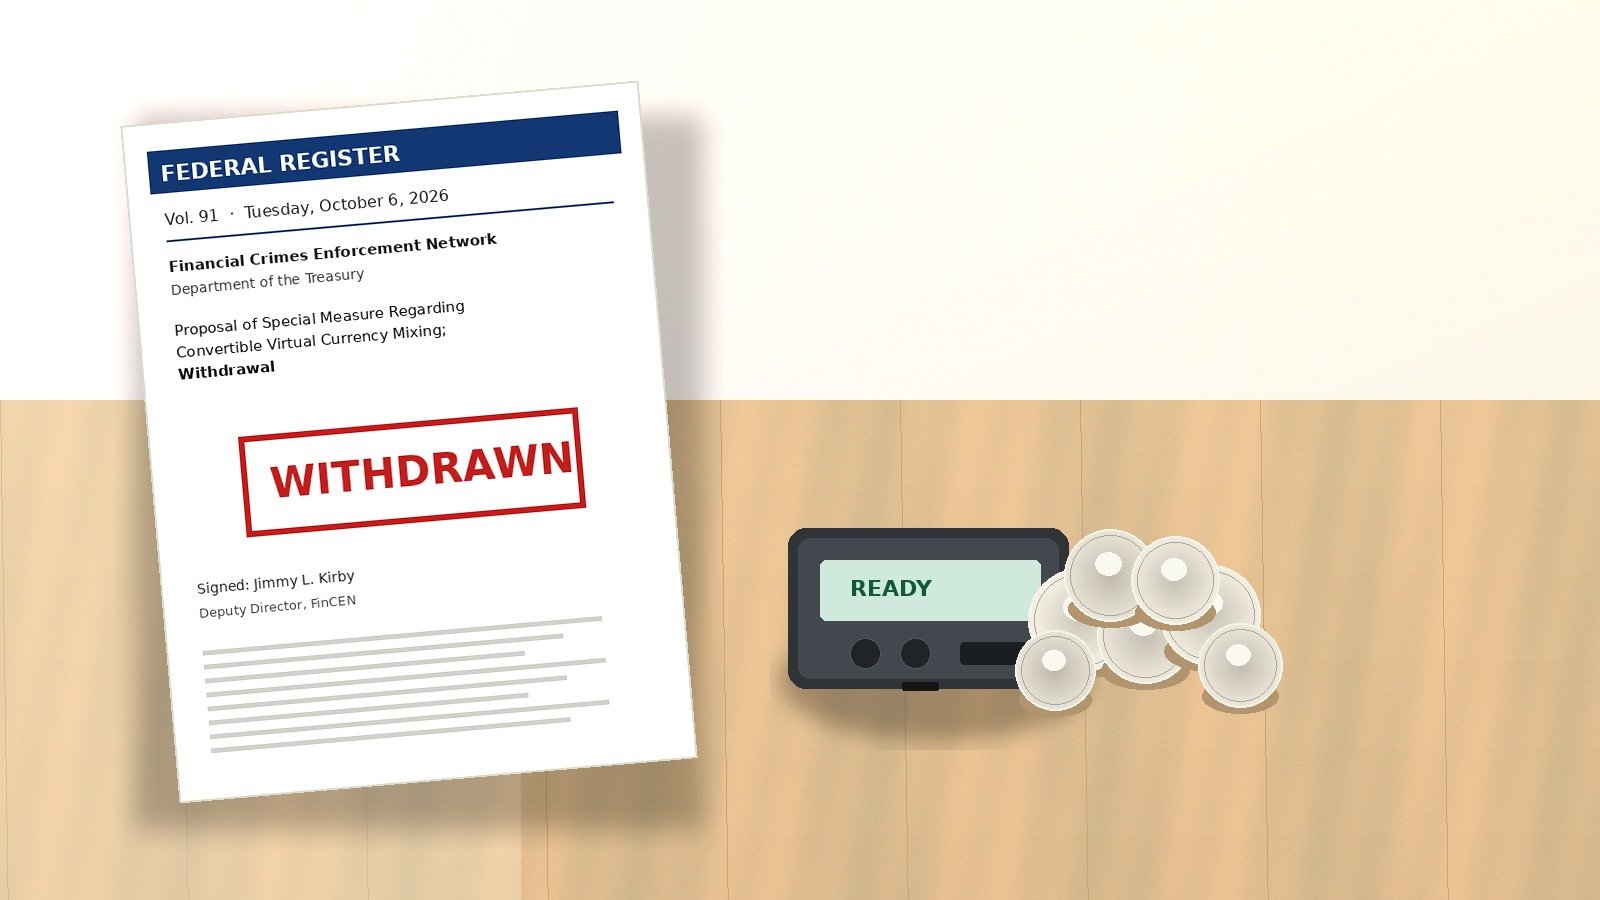
The Treasury Department’s Financial Crimes Enforcement Network formally withdrew two long-pending crypto proposals on Tuesday. The proposals would have required banks and money services businesses to collect and report more data on transactions tied to foreign crypto mixers and self-custodied wallets.
Both withdrawal notices were published in the Federal Register on Oct. 6 after going on public inspection Monday. Both are signed by FinCEN Deputy Director Jimmy L. Kirby.
The first withdraws FinCEN’s October 2023 finding, made under Section 311 of the USA PATRIOT Act, that international crypto mixing is “a class of transactions of primary money laundering concern,” along with the proposed rule attached to it. That rule would have required covered institutions to report mixing-linked transactions with details including wallet addresses, transaction hashes and IP addresses.
The second pulls a December 2020 proposal on “unhosted wallets.” It would have required banks and money services businesses to verify customers and keep records when a counterparty used a self-hosted wallet for transactions above $3,000, and to file reports above $10,000. “FinCEN will take no further action on this NPRM,” the notice says. Treasury’s regulatory agenda had already listed that proposal as withdrawn in 2024, Unchained reported; Tuesday’s notice makes it official.
Both notices cite the July 2025 report of the President’s Working Group on Digital Asset Markets. The mixer notice quotes the report’s line that the administration “supports the ability of lawful users of digital assets to privately transact on a public blockchain.” It also says commenters warned the broad definition of mixing “could have a chilling effect on legitimate activity and place a large reporting burden on covered financial institutions.”
What the notices don’t do matters as much. Neither proposal ever took effect, so current Bank Secrecy Act requirements stay as they are, and there is no new safe harbor for mixers. FinCEN said it “will continue to monitor activity involving CVC mixers” for illicit finance and “may take appropriate steps in the future.” Sanctions run on a separate track: on Oct. 2, Treasury’s Office of Foreign Assets Control designated a Hamas financing network that Treasury said moved money partly through crypto.
Coin Center, the policy group that filed comments against both proposals, called the move “a significant victory for financial privacy,” Unchained reported, citing a post by Coin Center’s Jason Somensatto.
For compliance teams, the practical change is smaller than the headlines suggest. A proposed reporting burden that had sat idle for years is now off the table, and the existing rulebook stays as written.
Sources: Federal Register mixer withdrawal (2026-20429); Federal Register unhosted-wallet withdrawal (2026-20430); Treasury OFAC press release (Oct. 2); The Block; Unchained.