
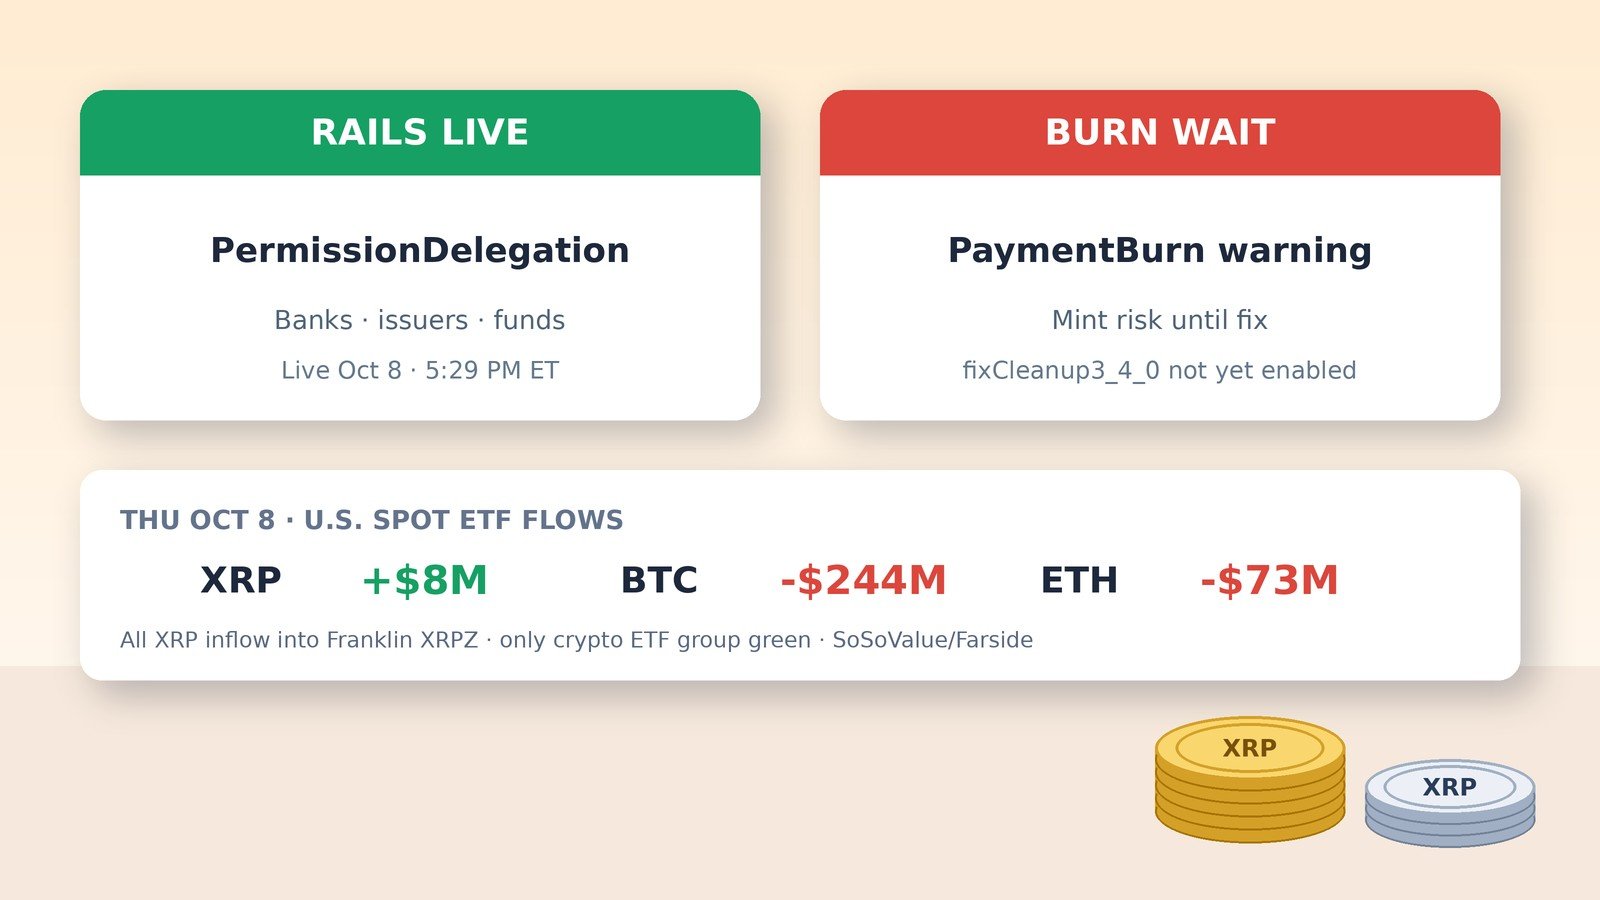
Opinion. Thursday evening the XRP Ledger flipped on bank-style permission splits. Account owners can now hand payments to one helper, compliance to another, and keep the master keys offline. CoinDesk called it new controls for banks, stablecoins and tokenized funds. Then look at the tape that hit the same window: U.S. spot XRP ETFs were the only crypto ETF group in the green, taking in about $8 million, while bitcoin funds lost about $244 million and ether funds about $73 million, per SoSoValue data in CoinDesk’s live updates.
Infrastructure PR on one side. Selective money on the other. Somebody is reading the fine print.
Rails got a role map. Burning did not.
PermissionDelegationV1_1 went live at ledger 107,524,865 on October 8, at 5:29 p.m. ET, per the ledger’s own record. That is real plumbing. Batch, the all-or-nothing bundling feature, is next in line Friday morning, if validator majorities hold. It is not live yet. A stablecoin desk can approve customers without parking the treasury key on the same laptop. Good.
Here is the part the launch thread often skips. Official XRPL docs still say do not delegate PaymentBurn until fixCleanup3_4_0 activates. Before that fix, a helper with burn rights can, in some cases, mint issued tokens. The ledger logged a majority for that cleanup early Friday, but the roll calls disagree: 28 of 35 on XRPL Dashboard, 27 of 35 per CoinDesk, with 29 needed. Even if it holds, the earliest it could switch on is around Oct. 23. So the ledger sold “bank controls” while one of the burn levers still carries a mint risk. Rails are live. Rails are not finished.
Who showed up with cash
On Thursday’s ETF tape, all of that XRP inflow went into Franklin Templeton’s XRPZ, which added about 6 million XRP. The other four XRP funds saw zero flow. Bitcoin ETFs were deep red after Wednesday’s $485 million outflow. Ether and SOL funds bled too. That is not “crypto risk-on.” That is one fund family catching the only green print while the rest of the complex paid the liquidation bill from a roughly $1.19 billion leveraged washout.
Follow the money, not the keynote. When institutions actually like a rail, they fund the wrapper that sits on top of it. On Thursday that wrapper was XRPZ, not a fresh round of “coming soon” bank pilots.
My read, labeled as a guess
Here is the speculation, and it is only that: the market is pricing finished distribution, not unfinished permission specs. Permission maps and offline master keys are what banks ask for in diligence decks. They are not the same as a named issuer running live customer approval on-ledger, and they are not the same as PaymentBurn being safe to hand to a helper. My guess is Franklin’s buyers were paying for ETF access and custody packaging, while the amendment headline bought attention that the burn warning still has to earn back.
To be clear, turning on role-based delegation is the right direction. Separation of duties belongs on these ledgers. The populist question is simpler: if the ledger needs a cleanup amendment before one burn permission is safe, why does the launch copy sound like the bank branch already opened? Watch two things: when fixCleanup3_4_0 clears the two-week bar, and whether XRP ETF inflows keep showing up on days bitcoin funds are dumping.
Sources: Farside Investors; XRPL.org Known Amendments; XRPL Dashboard; CoinDesk (PermissionDelegation); CoinDesk (ETF live updates); XRPL documentation