
Opinion. Yesterday a New Jersey bank put Ripple’s dollar stablecoin into its core operating system. By morning, half the timeline was selling you a story about Elon Musk’s payments app. Those are not the same announcement.
First, what’s real
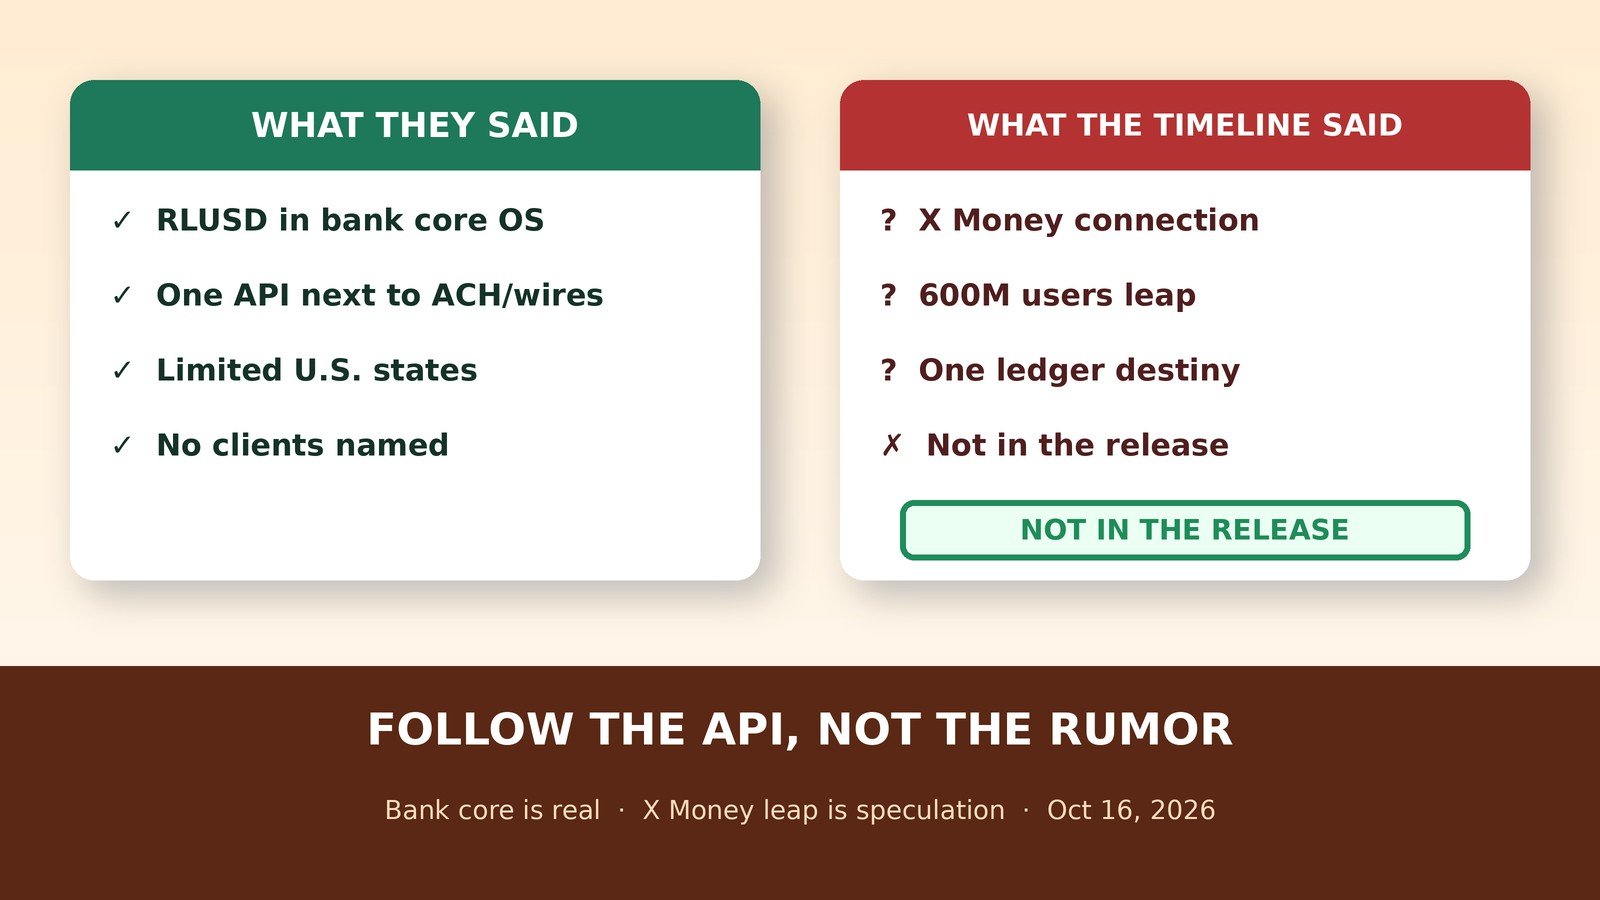
Cross River Bank said on Oct. 15 it is integrating RLUSD, Ripple’s U.S. dollar-backed stablecoin, into its proprietary Core Operating System, with support for transactions on the XRP Ledger. Eligible fintechs get the rail through one API, next to ACH, wires and real-time payments. The bank says it is live only in limited U.S. states. No client names. No volumes. No nationwide launch.
Ripple amplified the same deal on X. Cross River amplified it too. Neither company said a word about X Money, Musk, or a 600-million-user rocket.
What is true, separately: Cross River has been publicly described as providing banking infrastructure for X Money, the payments product tied to the X platform. That relationship is about fiat banking rails. It is not, on the public record, an RLUSD or XRP Ledger deal for X Money. CryptoRank and others have already noted the leap: confirmed bank + Ripple partnership, unconfirmed anything about X Money.
The pattern
Watch the sequence. Congress still hasn’t handed the market a finished digital-asset rulebook. Agencies fill gaps with notices and exemptions. And the actual plumbing keeps getting wired into places most retail holders never see: a bank’s core OS, a brokerage settlement plan in Europe, institutional custody in Dubai.
Then the attention economy does what it always does. It takes a dry bank press release and turns it into a meme about destiny. One bank becomes “the bank of X Money.” One API becomes “one ledger for 600 million users.” None of that was in the release.
Speculation, labeled
Speculation, labeled: this is how the new rails get built while you’re busy arguing about price targets. Quiet integration into regulated banking infrastructure. Loud secondary story that sounds like a consumer moonshot. My guess: the people writing the bank contracts are not the people drafting the viral threads, and the gap between those two groups is the product.
I’m not saying X Money will never touch a stablecoin. I’m saying nobody with a signature on this deal has said it will. Treating an unconfirmed retail fantasy as the headline is how you miss the real story: a regulated U.S. bank is putting a dollar stablecoin next to ACH inside the software fintechs already use. That is already a big deal. You don’t need to invent a bigger one.
And here’s the populist read, also labeled as my take: when the timeline sells you the fantasy version, it keeps you staring at the celebrity product while the settlement layer moves into the bank OS. Follow the API, not the rumor.
To be fair
Cross River really is an X Money banking partner in other reporting. Ripple really is pushing RLUSD into institutional rails this week. People are allowed to connect dots. They’re just not allowed to pretend the dots were in the press release. Westen’s desk has the factual write-up of what Cross River actually announced. Read that first. Then decide whether the timeline earned its leap.
This is opinion, not investment advice.
Sources: Cross River; Ripple; Cross River (X); CryptoRank