
Author: Easton

  • Wall Street Is Coming to Ripple’s House. Watch What It Buys, Not What It Says.

    Wall Street Is Coming to Ripple’s House. Watch What It Buys, Not What It Says.

    Opinion. Ripple’s Swell conference runs October 27–29 at The Shed in Manhattan, and on paper it’s the company’s biggest yet. Ripple’s own Swell site lists more than 1,500 attendees, more than 80 sessions, more than 100 speakers and three stages. For the first time, Ripple is folding in Apex, its XRP Ledger summit, and UBRI Connect, its university research conference.

    The guest list is the headline. Ripple’s lineup announcement names Laide Majiyagbe, BNY’s global head of markets; Michael Blaugrund, vice president of strategic initiatives at Intercontinental Exchange and a former NYSE chief operating officer; and Johann Kerbrat, who runs crypto and international at Robinhood. Bullish CEO Tom Farley and Ripple CEO Brad Garlinghouse are both on stage. Coverage from Coinpaper and Bitcoin News also lists CME Group chairman and CEO Terrence Duffy. Matt Damon and Water.org co-founder Gary White are there to talk about using Ripple Payments and RLUSD for water and sanitation funding.

    Credit where it’s due. When Swell started in 2017, Ripple was a crypto company asking banks to take its calls. This year, the people who run custody, exchanges and clearing are flying to Ripple’s event. That’s a real shift, and Ripple earned it.

    Now the part the hype accounts won’t tell you. Read the agenda topics: tokenized money market funds, stablecoins in “bank-grade production,” onchain collateral, settlement, liquidity. Most of that runs on dollars and tokenized securities, not on buying XRP. Even Coinpaper, which covered the lineup warmly, said Ripple’s growth “should not automatically be interpreted as increased demand for XRP,” because many institutional uses run on RLUSD or tokenized assets instead. The XRP Ledger’s proposed native lending feature still needs validator approval. A separate cleanup upgrade has slipped to a conditional November 4 activation target.

    Speculation, labeled: Wall Street usually shows up to a conference like this to learn what it can bring in-house, not to hand over the keys. When big incumbents talk about “the future of finance” on a crypto stage, the future they mean usually looks a lot like their present, with faster settlement. If that’s the takeaway from Swell, it’s good news for Ripple the company and the institutions that adopt it. Whether it’s good news for the retail XRP holder is a separate question that nobody on stage is paid to answer.

    Speculation, labeled: XRP community accounts tend to build up a “big announcement” before every Swell. Ripple has used the event to roll out products and partnerships before, so the hope isn’t crazy. But nothing has been confirmed. Coinpaper reports that Ripple and DriveWealth will hold an October 28 session on using RLUSD for brokerage funding and settlement, but no new product launch has been announced. If you’re trading on a headline that doesn’t exist yet, you’re the exit liquidity for the people who sold the rumor.

    What to watch this week: any signed, named deployment with dates and dollar amounts, any bank saying on the record that it will hold or settle in XRP itself, and any movement on the XRP Ledger’s lending amendment. Applause is free. Contracts aren’t.

    Sources: Swell 2026 official site; Ripple, “The Swell 2026 Lineup Is Here”; Coinpaper; Bitcoin News.

    This is opinion, not investment advice.
  • $150 Million Landed on the XRP Ledger. One Wallet Got All of It.

    $150 Million Landed on the XRP Ledger. One Wallet Got All of It.

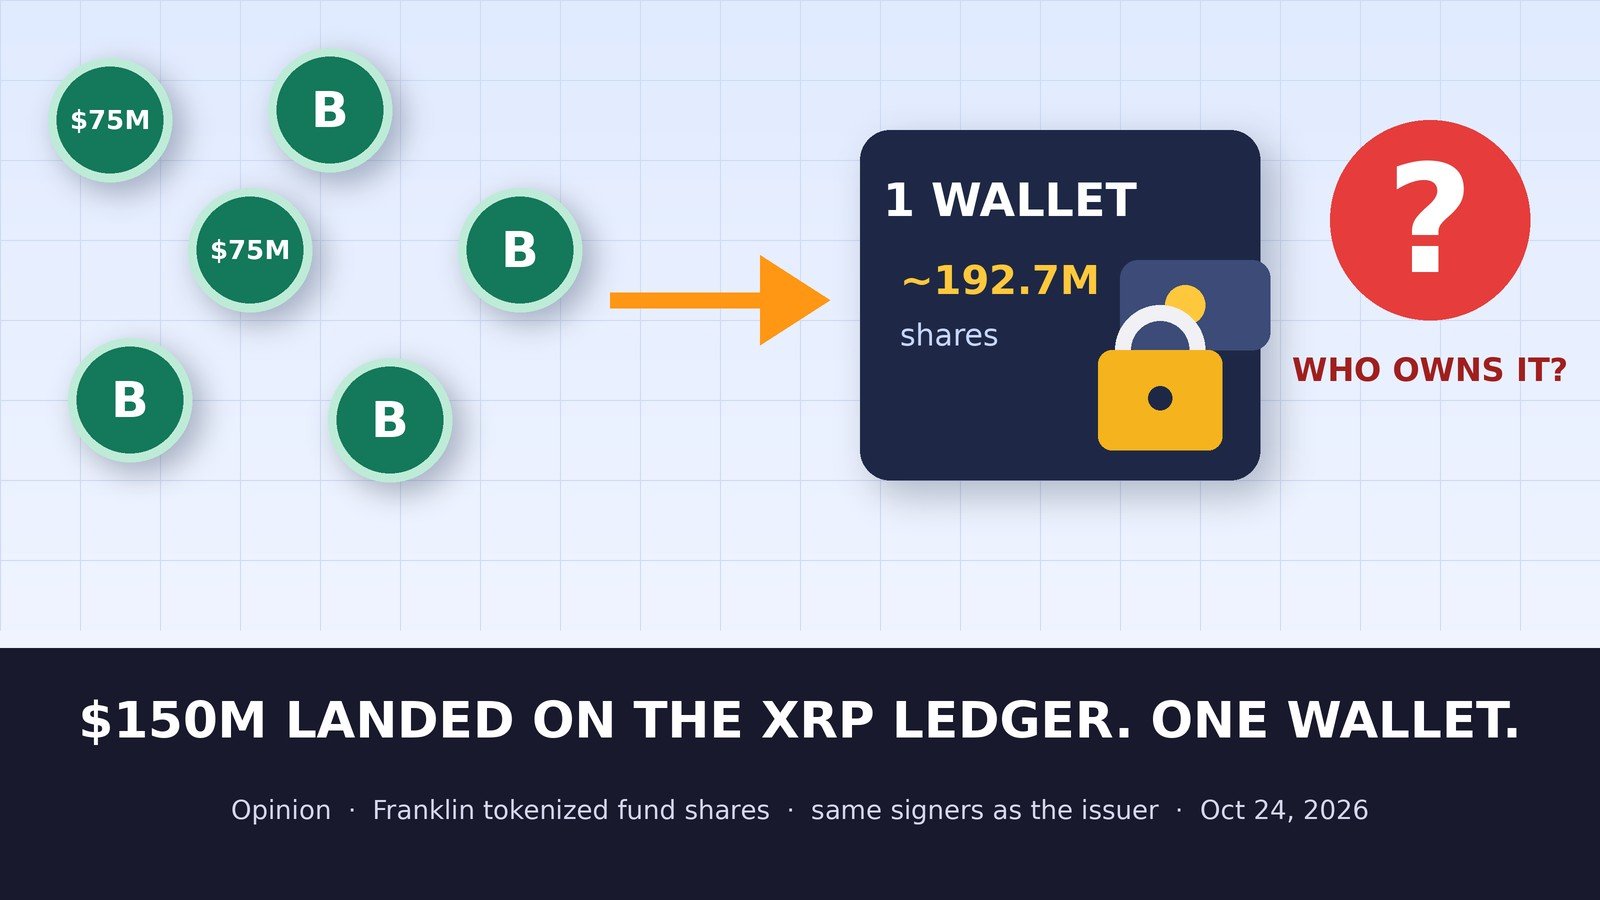
    The headline sounds like a win for the XRP Ledger: Franklin Templeton put about $150 million more of its tokenized money market fund on the chain this week. Read the fine print, though, and it looks less like a crowd rushing in and more like a big firm moving money through its own pipes.

    The facts first

    CoinDesk reported that Franklin’s issuing account recorded two $75 million cash subscriptions on the ledger. Two batches of just over 72.18 million shares each followed early Thursday, UTC, at a share price of $1.039.

    The fund is the Singapore-domiciled Franklin OnChain U.S. Dollar Short-Term Money Market Fund, ticker sgBENJI on the XRP Ledger. It holds short-term dollar debt such as government paper, commercial paper and bank deposits.

    Here’s the part that matters. Every one of those shares went to a single wallet. That wallet now holds all of the fund’s tokens on the XRP Ledger, roughly 192.7 million shares, or about $200 million at Thursday’s price.

    We checked the public ledger ourselves Saturday morning. The receiving wallet and Franklin’s issuing account list the same eight signing addresses, and any two of them can approve a transaction. The token’s settings require Franklin’s approval to hold it, and let Franklin lock balances and claw tokens back.

    CoinDesk asked Franklin whether the wallet is an omnibus account, how many investors are behind the money, and whether they’ll ever get their own addresses. Franklin had not responded by the time CoinDesk published.

    Why it bugs me

    Crypto was sold to regular people as money nobody could freeze, run on a ledger anyone could check. What we’re getting from Wall Street is the opposite: the ledger is public, but the gate, the keys and the off switch all stay with the issuer.

    To be fair, none of that is hidden. Franklin’s fund documents describe a register that links ledger entries to real-world identities kept off-chain. Brokers hold shares for many clients in one account every day. Freeze and clawback powers are standard for a regulated fund.

    But “regulated and normal” is not the same thing as “adoption.” When $150 million lands in one wallet controlled by the same signers as the issuer, the chain is mostly acting as Franklin’s filing cabinet.

    Speculation, clearly labeled

    This is speculation, not reporting: my guess is this wallet is a holding account Franklin or its distribution partners run for clients, not $150 million of fresh outside demand for XRP Ledger products. If so, the “XRPL just got $150 million” posts are cheering a bookkeeping entry. I could be wrong. Franklin can settle it with one sentence about who owns the shares.

    Also worth saying for XRP holders: the coin itself barely figures here. These tokens pay tiny network fees in XRP and nothing more. The XRP Ledger’s own lending tools, which would let funds like this be pooled and lent on-chain, still don’t have the validator votes to switch on.

    Tokenized funds may well be the future of the plumbing. I just want the plumbing labeled honestly. Show us how many holders there are, not just how many dollars.

    Sources: CoinDesk; XRP Ledger public records (XRPSCAN, XRPL mainnet nodes); Franklin Templeton fund documents (as cited by CoinDesk); RWA.xyz.

    This is opinion, not investment advice.

  • ‘Not True at Present Time’ Is Doing a Lot of Work in the Visa–Fireblocks Rumor

    ‘Not True at Present Time’ Is Doing a Lot of Work in the Visa–Fireblocks Rumor

    Opinion. Let’s start with what’s known, because it’s not much. On Thursday, Axios reported, citing multiple unnamed sources, that Visa is in late-stage talks to acquire Fireblocks for about $2.5 billion. Fireblocks provides stablecoin infrastructure and crypto custody to institutions. Within hours, a Fireblocks spokesperson told CoinDesk: “We are aware of the rumors about a possible acquisition of Fireblocks by Visa. This is news to us, and not true at present time.” Visa declined to comment. Coinbase, which anonymous sources had told CoinDesk was also in the frame as a buyer, denied that it was involved.

    So, to be clear up front, this is an unconfirmed report that has been denied by the company being sold. Nobody has signed anything that anyone has shown the public.

    Still, read that denial again. “Not true at present time.” It isn’t “false,” and it isn’t “we are not for sale.” It’s a statement about today. Companies choose those words carefully, and these ones leave the door wide open. Speculation, labeled: when a company’s denial carries an expiration date, the market is right to treat it as a pause, not a no.

    The number is the real story, if it turns out to be real. In 2022, Fireblocks raised $550 million at an $8 billion valuation. A $2.5 billion sale would be less than a third of that. CoinDesk also reports that talk of a possible sale has been circulating for three to four weeks. Speculation, labeled: a down-round exit would tell you the 2021–22 private crypto marks were never as solid as the press releases made them sound. Somebody will be taking a haircut, and it won’t be announced with a cheerful blog post.

    Then there’s the strategic question. Axios framed the report around traditional finance picking up the pace of stablecoin adoption. Picture what that means in practice. Fireblocks says on its own profile that more than 2,500 institutions use it for stablecoins, custody and digital asset operations. Put that plumbing inside one of the biggest card networks on the planet, and the “decentralized” future starts running through the same tollbooth as the old one.

    Speculation, labeled: this is what institutional adoption usually looks like. Not a revolution, but the incumbents buying the rails before the public notices the rails matter. Nobody will vote on it, and nobody will be asked. It’ll show up as a closed deal and a press release about “innovation.”

    To be fair to everyone involved: Fireblocks has built real infrastructure that serious institutions rely on, and Visa has been open about working with stablecoins. If a deal happens, it could make crypto payments easier for ordinary people. That’s a genuine upside. But who holds the keys matters, and it’s worth asking before the ink dries, not after.

    For now: watch for a Visa filing or a formal statement, and watch whether that “at present time” language changes. Until then, it’s a rumor with a denial attached, and you should treat it that way.

    Sources: Axios; CoinDesk; Fireblocks

    This is opinion, not investment advice.
  • Wall Street’s Biggest Names Don’t Want Their Stock Trading at 3 A.M. Ask Who That Protects

    Wall Street’s Biggest Names Don’t Want Their Stock Trading at 3 A.M. Ask Who That Protects

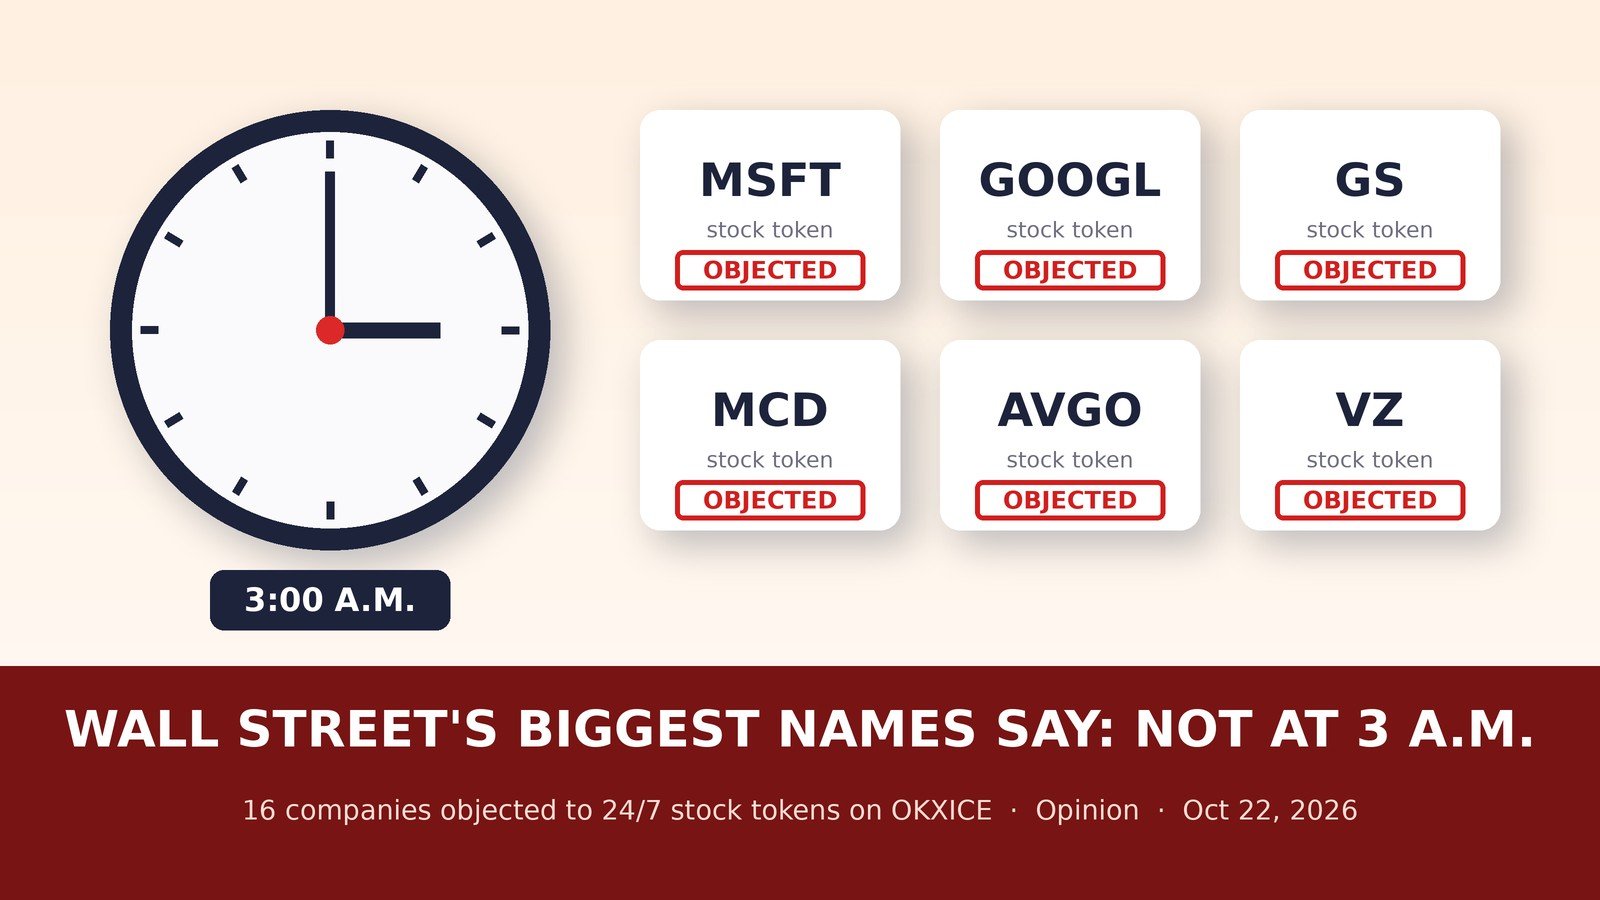
    Opinion. Imagine it’s 3 a.m. on a Sunday. Big news breaks. You want to buy or sell a slice of Microsoft right now, not on Monday morning. A new venue backed by the owner of the New York Stock Exchange says it can make that happen. Microsoft, Alphabet and Goldman Sachs have officially said: not with our stock.

    First, what’s real

    OKXICE is a 50-50 joint venture between crypto exchange OKX and Intercontinental Exchange, the NYSE’s parent. It wants to run a “tokenized securities venue” that trades blockchain versions of U.S. stocks 24 hours a day, seven days a week. Each token is paired with a dollar stablecoin, either USDC, USDG or USDT, and trades in Uniswap v4 pools on OKX’s XLayer network, according to the venue’s public notice.

    The SEC opened this door last month with a temporary exemption. The catch: companies get 30 days after being notified to object. If they object, their token can’t trade on that venue under the exemption.

    As of OKXICE’s Oct. 19 notice, 16 companies had objected: Cerebras, AppLovin, Applied Digital, Rocket Lab, CoreWeave, Verizon, Applied Optoelectronics, Broadcom, UnitedHealth, Goldman Sachs, Microsoft, Qualcomm, Caterpillar, McDonald’s, Western Digital and Alphabet. OKXICE had planned to offer more than 60 stocks. Fortune reports Apple, Nvidia and Amazon are among those that haven’t objected yet, and some companies have until early November.

    Speculation, labeled

    Speculation, labeled: my read is that big companies like a stock market with a bedtime. When the market closes, they get quiet hours to release earnings and let the news sink in. A market that never sleeps takes that cushion away. A lawyer at Morgan Lewis told Fortune exactly that: companies would lose the pause they normally use to announce earnings. That’s a real concern. It’s also a concern about control, not about protecting you.

    Also speculation, labeled: notice who’s on the list. Goldman Sachs isn’t just a stock. It’s one of the biggest trading houses on Wall Street. I can’t prove why Goldman objected. It didn’t say, and neither did 14 of the others. But when the firms that profit most from today’s market plumbing are first in line to say “not yet” to new plumbing, regular people are allowed to raise an eyebrow.

    And let’s not pretend OKXICE is the people’s champion either. It’s co-chaired by former New York Gov. Andrew Cuomo. It’s a joint venture with the NYSE’s own parent. And only wallets holding a special permission token can trade there, its notice says. This isn’t Main Street storming Wall Street. It’s two sets of insiders arguing over who runs the new toll road.

    To be fair

    The objectors have real points. Prices in these pools come from a formula and can drift from the real stock price, especially when trading is thin. Applied Optoelectronics, the only company that explained itself to Fortune, said the effects on its share price, liquidity and volatility are unclear, and that investors might wrongly think it backed the product.

    The objections also don’t stop tokenized stocks from growing. They only block trading on this one venue under this one exemption. Tokenized stock volume on Robinhood Chain jumped to $11.31 billion in September from $526 million in July, CNBC reported, citing Bitwise. Cuomo called the objections “a very natural response” and said many companies want to “wait and see.”

    Fine. But “wait and see” from the biggest names in America sounds a lot like “wait until we figure out how to own it.” If 24/7 trading is coming anyway, the question is simple: does it come built for you, or built for them?

    This is opinion, not investment advice.
    Sources: OKXICE public notice (Oct. 19); SEC; Fortune; CNBC; CoinDesk; Cointelegraph

  • Six Months in Plain Sight: The Drift Hack Money Is Finally Moving

    Six Months in Plain Sight: The Drift Hack Money Is Finally Moving

    Opinion. On Tuesday, after about two months of silence, wallets labeled as the Drift Protocol exploiter sent 25,700 ETH, about $61.6 million, into Tornado Cash over roughly two hours, according to Lookonchain. Arkham data cited by Cointelegraph shows the exploiter’s addresses still holding about 81,450 ETH, worth roughly $194 million. Drift says it lost about $295 million in the April 1 attack on the Solana-based exchange. In June, Drift said a Mandiant investigation attributed the attack to UNC6862, a North Korean threat group.

    Update, Oct. 21: A second batch of ETH from the exploiter’s wallets moved into Tornado Cash on Wednesday morning, so the remaining balance is now lower than the figure above. Trackers differ on the size of the new batch.

    Here’s the part that should bother people. This money hasn’t been hiding. Drift’s own September update laid out the trail: the stolen funds were bridged to Ethereum and split across four wallets holding about 130,259 ETH. One wallet sent about 23,094 ETH to Tornado Cash on July 23. The other three, holding 107,165 ETH, hadn’t moved at all. For six months, everyone could see the wallets, the labels and the balances. Drift says about $9.2 million has been frozen so far. That’s roughly 3% of the loss.

    Tuesday’s move came from that untouched pile. Subtract 25,700 from 107,165 and you land near the 81,450 ETH Arkham still shows, so the numbers line up.

    Don’t let the story turn into “ban the mixer” again. Washington already tried that. Treasury sanctioned Tornado Cash in 2022, then lifted those sanctions in March 2025 after the Fifth Circuit ruled that its immutable smart contracts weren’t property that could be blocked. A state-linked hacking group was always going to find a laundering route. The real question is why nine figures of attributed stolen ether could sit untouched on a public ledger for half a year while the recovery tally barely moved. Speculation, labeled: freezing works at the edges, at exchanges and stablecoin issuers, and patient attackers simply wait until attention fades before they walk through the middle. Tuesday looks like that playbook.

    The victims are left with a bounty program and a recovery pool. Drift has partnered with Bybit on a 10% bounty for recovered funds, and its DFX recovery tokens opened for claims on October 1, backed by a pool that held about $3.1 million at launch. That’s a long way from $295 million.

    Now the market angle, and it’s all speculation, labeled: money that goes into a mixer usually doesn’t hit the order book right away. It comes out in pieces and often gets swapped into other assets through bridges or over-the-counter desks. If the remaining ~81,500 ETH follows, that’s about $194 million that could eventually be sold. That’s a real number, but it’s spread over weeks or months and set against a deep ETH market. Watch the outflows and the bridges. Don’t treat one headline as a sell signal.

    Hardwire’s read: give the on-chain sleuths credit, because they caught this in real time. Then ask why catching it isn’t the same as stopping it. Six months of open-ledger visibility recovered about 3% of the loss. That isn’t a privacy problem. It’s an enforcement problem.

    This is opinion, not investment advice.

    Sources: Cointelegraph; Lookonchain; Lookonchain; Arkham

  • Your Savings Bank Now Sells XRP. It Also Keeps the Keys

    Your Savings Bank Now Sells XRP. It Also Keeps the Keys

    Opinion. Germany’s savings banks spent years telling customers crypto was too risky to touch. On Monday, the first of them started selling it right inside the banking app. Bitcoin, Ether, XRP, Solana, Polygon. Ninety-nine cents an order. Sounds like a win for crypto. Read the fine print first.

    First, what’s real

    The service, “Krypto – powered by Deka,” runs through DekaBank, the securities house of the Sparkassen. Westen’s desk has the straight write-up. Read that first.

    The key facts come from DekaBank’s own product page. Your coins sit in a shared “omnibus” wallet. DekaBank holds the private keys in trust. And coins can only be sent out to wallet addresses of certain licensed crypto service providers. Sending them anywhere else, like a hardware wallet in your drawer, is excluded.

    The €0.99 fee is real, and it’s cheap on bigger orders. But your price also includes a DekaBank spread on top of a market reference price, and the published documents don’t put a number on it, as CryptoCompass pointed out. According to that report, the price list also says pricing can be adjusted, for example through the spread, when volumes are large or markets get wild.

    Speculation, labeled

    Speculation, labeled: my read is the banks didn’t fall in love with crypto. They watched younger customers buy it at Trade Republic, N26 and Revolut, and decided it was better to keep that money in the house. The savings banks association more or less says so itself: it points to customer demand.

    Also speculation, labeled: this looks like the template for how big banks tame crypto. You get the price exposure. The bank gets the fee, the spread, the customer and the keys. The one thing crypto was built to give you, holding your own money without asking anyone’s permission, is the one thing this product leaves out. A wallet you can only leave through approved doors starts to look a lot like the bank account crypto was supposed to replace.

    Americans should watch this closely. JPMorgan’s JPM Coin, which just headed to Ethereum, follows the same idea at the institutional level: public blockchain rails, bank-controlled access. I’m not saying anyone coordinated it. Pooled custody is normal at big exchanges too, and rules like the EU’s MiCA push banks toward caution. But when “crypto at your bank” means “the bank holds your crypto, and you leave only through doors it approves,” it’s fair to ask whose freedom just got the upgrade.

    To be fair

    This is a regulated, simple way for ordinary savers to buy a little crypto, with honest warnings about total loss. Sending coins out to an approved provider is free, according to CryptoCompass’s reading of the price list, and many exchanges then let you move coins on to your own wallet. For a lot of people, a bank they already know beats a random offshore app. And it puts XRP, Solana and Polygon in front of a customer base of around 50 million, which some holders will cheer.

    Just know what you’re buying: price exposure, held by the bank. If you want the keys, you’ll have to take the long way around.

    This is opinion, not investment advice.
    Sources: Deka Krypto product page; DekaBank; CryptoCompass; dpa-AFX (via finanzen.net); DSGV; The Block

  • JPMorgan Wants Ethereum’s Rails. Wall Street Keeps Selling the Ether

    JPMorgan Wants Ethereum’s Rails. Wall Street Keeps Selling the Ether

    Opinion. On Monday the timeline lit up with one headline: JPMorgan is taking its JPM Coin onto Ethereum. Big bank, public chain, 24/7 money. Bullish, right? Then look at what Wall Street has been doing with ether itself.

    First, what’s real

    JPMorgan’s blockchain unit, Kinexys, says its dollar deposit token, JPMD, now supports transfers on Ethereum as well as Base. It is for approved institutional clients only. The bank’s own FAQ says it is “not a cryptocurrency or a stablecoin.” It is a JPMorgan deposit that moves on a blockchain, and only vetted counterparties can touch it. Westen’s desk has the straight write-up. Read that first.

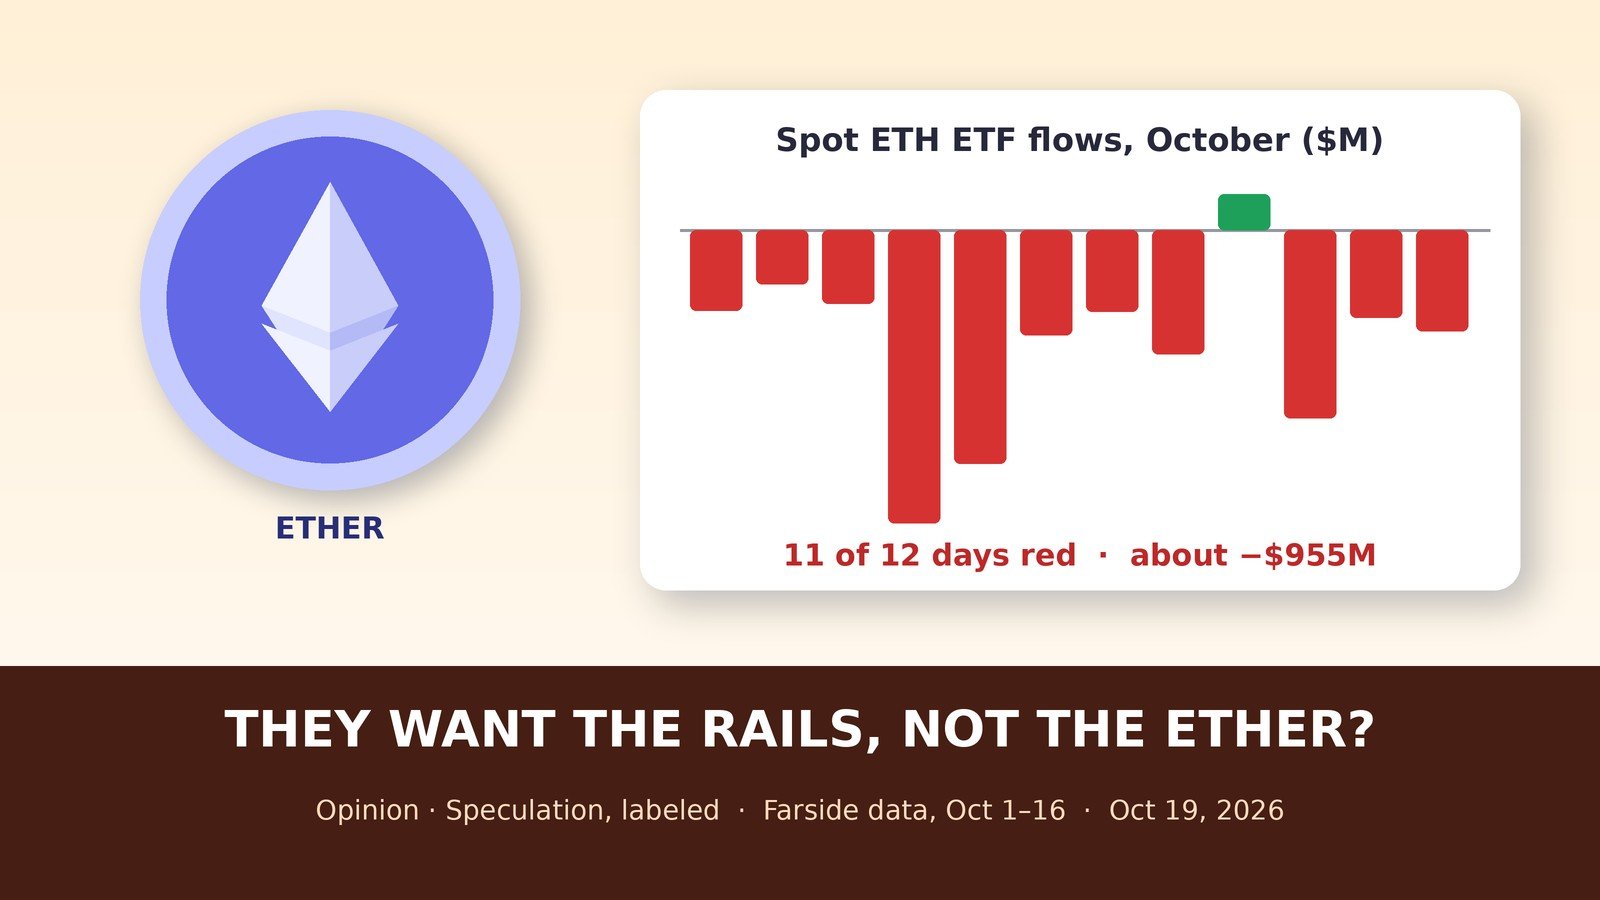
    Now the flows. U.S. spot ether ETFs have seen net outflows on 11 of the 12 trading days in October so far, per Farside Investors data. The total through Oct. 16 is about $955 million out. BlackRock’s ETHA, the biggest ether fund, accounts for roughly $796 million of that. The only green day was Oct. 13, at $24.8 million in.

    Speculation, labeled

    Speculation, labeled: my read is that the big money wants Ethereum’s rails, not its coin. The banks are happy to run their own dollars on the highway. They are much less excited about owning the asphalt.

    Think about who wins in this setup. JPMorgan keeps the deposit, the customer and the interest margin. The token never leaves its banking system. The public chain gets used as plumbing. Meanwhile, the ETF crowd that was supposed to be the steady bid for ether has been heading for the exits almost every day this month.

    I’m not saying anyone is coordinating that. ETF flows have plenty of boring causes: hedge funds unwinding trades, rebalancing, people moving to cash in a rough tape. But when the biggest bank in the country shows up on Ethereum the same month the biggest ether fund keeps redeeming, it’s fair to ask whether “institutions are coming” means what retail thinks it means.

    To be fair

    Every transfer on Ethereum’s main network pays a fee in ether, so real bank traffic would mean some real demand for the coin. JPMorgan also put two tokenized money market funds on Ethereum before this, so it is not a one-off. And a few weeks of outflows can flip fast; ether was trading around $2,420 on Monday morning, up slightly on the day. But if your thesis is “banks on Ethereum means ether goes up,” the ETF tape this month says the banks haven’t signed that part.

    This is opinion, not investment advice.

    Sources: Farside Investors; The Block; CoinDesk; J.P. Morgan Kinexys; Watcher.Guru (X)

  • Three Banks, One Coin, Every Holder ID’d. Is This the CBDC Nobody Voted For?

    Three Banks, One Coin, Every Holder ID’d. Is This the CBDC Nobody Voted For?

    Opinion. The headline on the timeline said Japan’s three biggest banks just ran a “crypto stablecoin payment” test. Read the fine print and it sounds a lot less like crypto and a lot more like the banks.

    First, what’s real

    MUFG, Mizuho and SMBC said on Oct. 16 that a jointly issued yen stablecoin worked in a one-week test in July. It moved money between Mitsubishi Corporation’s offices in Japan and overseas. The money behind it sits in bank deposits. A bank provided the blockchain. And the coin is designed to move only among people who have passed identity checks at the banks. The banks are aiming for live transactions in fiscal 2026, which ends in March 2027.

    That is a real step for bank payments. Westen’s desk has the straight write-up. Read that first.

    The part nobody put in the headline

    Think about what the design adds up to. Three giant banks issue one coin. Only ID-checked users can hold it. The banks run the platform it lives on. And there is no circulation cap, because they expect it to be used at scale.

    That is not the cypherpunk dream. Nobody is opting out of anything. It is digital money where the issuer knows who holds every coin, on rails the issuer controls.

    Speculation, labeled

    Speculation, labeled: my read is that this is how you get most of what a central bank digital currency would give the state, without anyone ever voting on a CBDC. You don’t need a government coin if the biggest banks, with a government regulator’s support, issue an ID-only coin and everyone’s payroll and invoices slowly move onto it.

    I’m not saying anyone in Tokyo is plotting a surveillance state. I’m saying the plumbing is the policy. Once money is programmable and every holder is known, the question of what that money can be stopped from doing gets answered by whoever writes the code and the rules, not by the person holding it.

    And it’s not just Japan. In the same week, a U.S. bank wired a dollar stablecoin into its core system and Visa moved stablecoin funding into production. Those are permissioned, compliance-first rails too. Plenty of people cheering “adoption” may be cheering the banks taking the stablecoin back.

    To be fair

    Identity checks exist for real reasons, like fraud and money laundering, and regulators expect them. A deposit-backed bank coin may well be safer for a company like Mitsubishi than an offshore token. And this was a test, with the design still open to change. But if you got into crypto to hold money nobody else controls, a bank-run, ID-only coin is a different product. Know which one you’re cheering for.

    This is opinion, not investment advice.
    Sources: MUFG Bank; Trade Finance Global; Watcher.Guru (X); Visa

  • They Wired a Stablecoin Into a Bank Core. Then the Timeline Sold You X Money

    They Wired a Stablecoin Into a Bank Core. Then the Timeline Sold You X Money

    Opinion. Yesterday a New Jersey bank put Ripple’s dollar stablecoin into its core operating system. By morning, half the timeline was selling you a story about Elon Musk’s payments app. Those are not the same announcement.

    First, what’s real

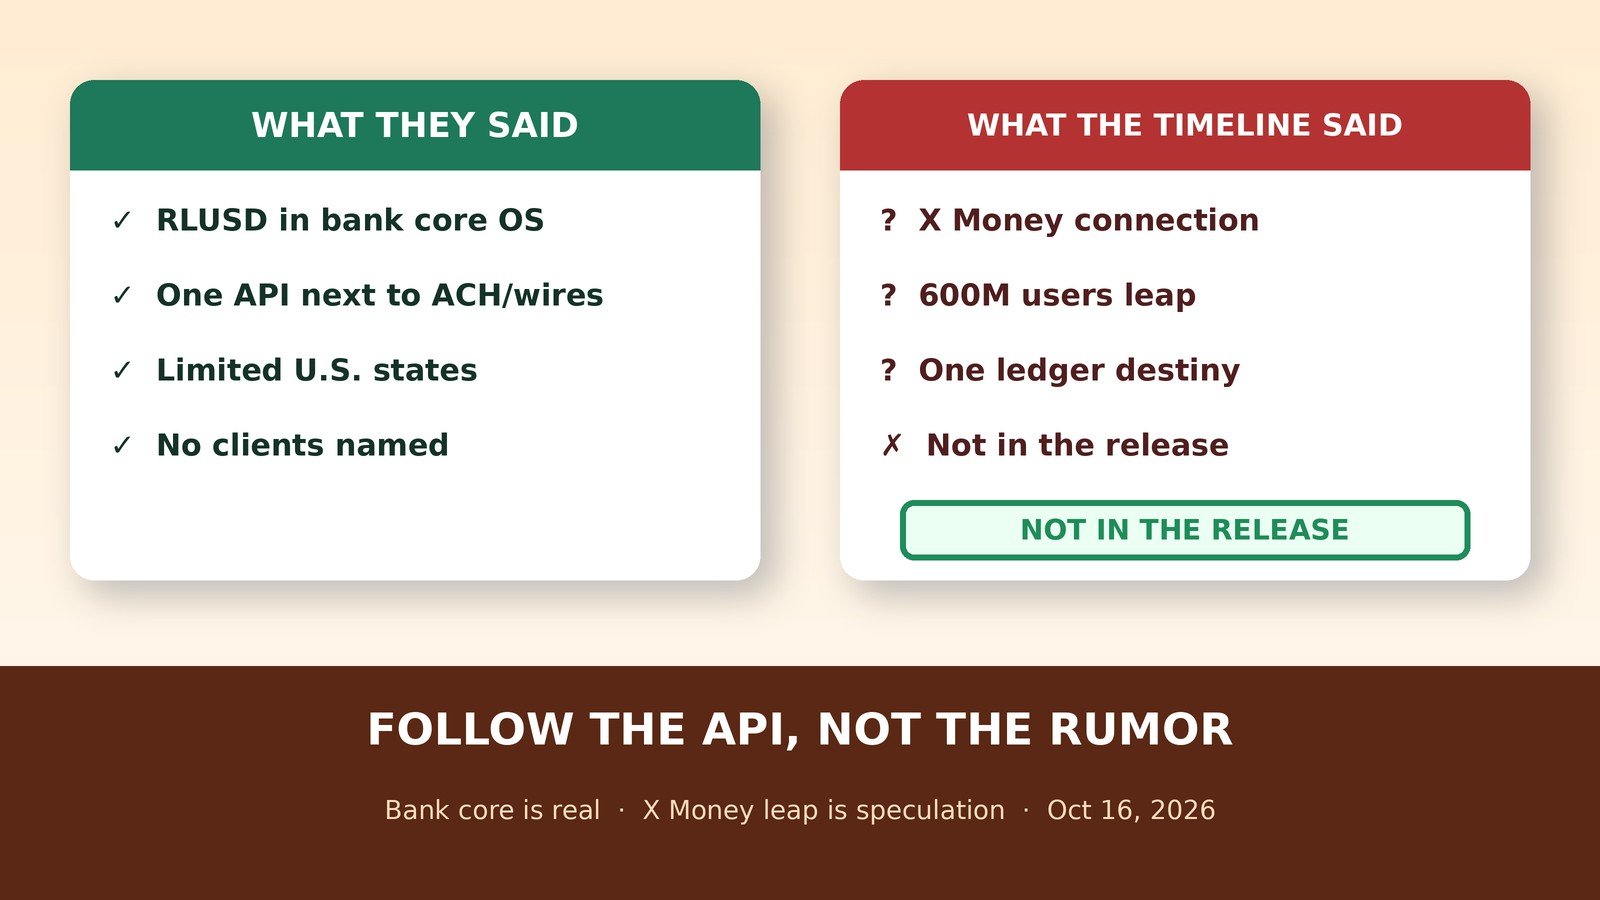
    Cross River Bank said on Oct. 15 it is integrating RLUSD, Ripple’s U.S. dollar-backed stablecoin, into its proprietary Core Operating System, with support for transactions on the XRP Ledger. Eligible fintechs get the rail through one API, next to ACH, wires and real-time payments. The bank says it is live only in limited U.S. states. No client names. No volumes. No nationwide launch.

    Ripple amplified the same deal on X. Cross River amplified it too. Neither company said a word about X Money, Musk, or a 600-million-user rocket.

    What is true, separately: Cross River has been publicly described as providing banking infrastructure for X Money, the payments product tied to the X platform. That relationship is about fiat banking rails. It is not, on the public record, an RLUSD or XRP Ledger deal for X Money. CryptoRank and others have already noted the leap: confirmed bank + Ripple partnership, unconfirmed anything about X Money.

    The pattern

    Watch the sequence. Congress still hasn’t handed the market a finished digital-asset rulebook. Agencies fill gaps with notices and exemptions. And the actual plumbing keeps getting wired into places most retail holders never see: a bank’s core OS, a brokerage settlement plan in Europe, institutional custody in Dubai.

    Then the attention economy does what it always does. It takes a dry bank press release and turns it into a meme about destiny. One bank becomes “the bank of X Money.” One API becomes “one ledger for 600 million users.” None of that was in the release.

    Speculation, labeled

    Speculation, labeled: this is how the new rails get built while you’re busy arguing about price targets. Quiet integration into regulated banking infrastructure. Loud secondary story that sounds like a consumer moonshot. My guess: the people writing the bank contracts are not the people drafting the viral threads, and the gap between those two groups is the product.

    I’m not saying X Money will never touch a stablecoin. I’m saying nobody with a signature on this deal has said it will. Treating an unconfirmed retail fantasy as the headline is how you miss the real story: a regulated U.S. bank is putting a dollar stablecoin next to ACH inside the software fintechs already use. That is already a big deal. You don’t need to invent a bigger one.

    And here’s the populist read, also labeled as my take: when the timeline sells you the fantasy version, it keeps you staring at the celebrity product while the settlement layer moves into the bank OS. Follow the API, not the rumor.

    To be fair

    Cross River really is an X Money banking partner in other reporting. Ripple really is pushing RLUSD into institutional rails this week. People are allowed to connect dots. They’re just not allowed to pretend the dots were in the press release. Westen’s desk has the factual write-up of what Cross River actually announced. Read that first. Then decide whether the timeline earned its leap.

    This is opinion, not investment advice.

    Sources: Cross River; Ripple; Cross River (X); CryptoRank

  • France Wants to Tax You for Using the Stablecoins Europe Told You to Use

    France Wants to Tax You for Using the Stablecoins Europe Told You to Use

    Opinion. For years, Brussels told Europeans the same thing: use the regulated stablecoins. The licensed ones, the supervised ones, the ones that report to the tax man. Now a group of French lawmakers wants to charge you 31.4% for doing exactly that.

    First, what’s real

    On Oct. 7, the National Assembly’s finance committee adopted an amendment from Nicolas Sansu of the left-wing GDR group. It would end the tax pause on swapping crypto into e-money tokens, MiCA’s name for stablecoins pegged to one currency, like USDC. Starting Jan. 1, 2027, that swap would trigger France’s 31.4% flat tax on gains. Today, crypto-to-crypto swaps in France aren’t taxed until you cash out to euros or spend.

    Two days later, the committee rejected the whole revenue half of the budget, 31 to 3. Under French budget rules, the floor debate restarts from the government’s text, which doesn’t include the amendment. It is not law.

    But it isn’t dead either. On Oct. 10, Sansu refiled the same text for the full Assembly as amendment I-3898. It’s on the list to be debated. The vote on the revenue half of the budget is set for Tuesday, Oct. 20.

    Taxing the lane they built

    Do the simple math. Lock in a €40,000 gain by moving into a regulated stablecoin, and at 31.4% you’d owe €12,560, even though not a single euro reached your bank account.

    The amendment’s own explanation calls the current rule a “hole in the legislation” and says taxing the swap is just “a simple application of tax law that already exists” (our translation). Maybe. But look at the timing. On Oct. 8, the EU’s markets regulator, ESMA, told licensed crypto firms to stop offering services in stablecoins that don’t comply with MiCA, and gave supervisors three months to clean up what’s left. And on Wednesday, the European Banking Authority named USDC the EU’s first “significant” e-money token, putting its reserves under EU-level watch.

    So Europe is herding people into the regulated stablecoins, and Paris is drafting a toll at the door. Francois Volpoet, Chainalysis’s regional sales director for France, told CoinDesk the measure could push people toward DeFi, peer-to-peer trades and exchanges outside international tax reporting. He also noted it targets MiCA-compliant stablecoins and may leave other tokens outside its scope. Tax the compliant lane, and you shouldn’t be surprised when traffic moves to the dirt road.

    Speculation, labeled

    Speculation, labeled: this looks less like stablecoin policy and more like a treasury hunting for any gain it can call “realized.” The same committee also backed a rule making people declare self-custody wallets holding €100,000 or more, and an exit tax on large crypto holdings when people move abroad. Put it together and the message to French holders reads like this: stay, report everything, pay early, or pay on the way out.

    And here’s my guess about who actually pays. The whales, the funds and the big desks have lawyers, offshore entities and the option to move. The regular saver on a French app doesn’t. A tax like this doesn’t stop big money from moving. It just makes sure the little guy is the one who sends the check. That’s my read, not a fact. But it’s worth watching who lines up behind this on Oct. 20.

    One more thing nobody should wave away: Chainalysis counted 30 violent attacks on crypto holders in France in the first half of this year, according to CoinDesk. A government list of everyone with €100,000 in a wallet is a list somebody will want to steal.

    To be fair

    There’s pushback on the record. Deputy Daniel Grenon filed the opposite amendment for the floor, I-3738, which would keep swaps into e-money tokens tax-free. His stated reason: taxing them would hit French holders directly and make platforms based in France less attractive. The committee also voted to let investors carry crypto losses forward for 10 years. And French budgets don’t always survive the floor. Last year, the Assembly voted down the revenue half of the budget outright.

    So watch Oct. 20. If the swap tax gets back in and survives, Europe will have built a regulated stablecoin market and then charged people for using it. If it dies, credit the deputies who noticed that you don’t bring money onshore by taxing it at the door.

    This is opinion, not investment or tax advice.

    Sources: Assemblée nationale (amendment I-3898); Assemblée nationale (amendment I-CF1826); Assemblée nationale (amendment I-3738); CoinDesk; ESMA; European Banking Authority; NosParlementaires; Cryptoast