Opinion. Ripple and CSD BR announced on September 29 that Brazil’s central securities depository is using the XRP Ledger as an extra layer to record and audit financial assets — starting with selected BTG Pactual investment fund shares, tokenized under XRPL’s Multi-Purpose Token standard. That is a real infrastructure story. It is also a story the market will try to inflate into something it is not.
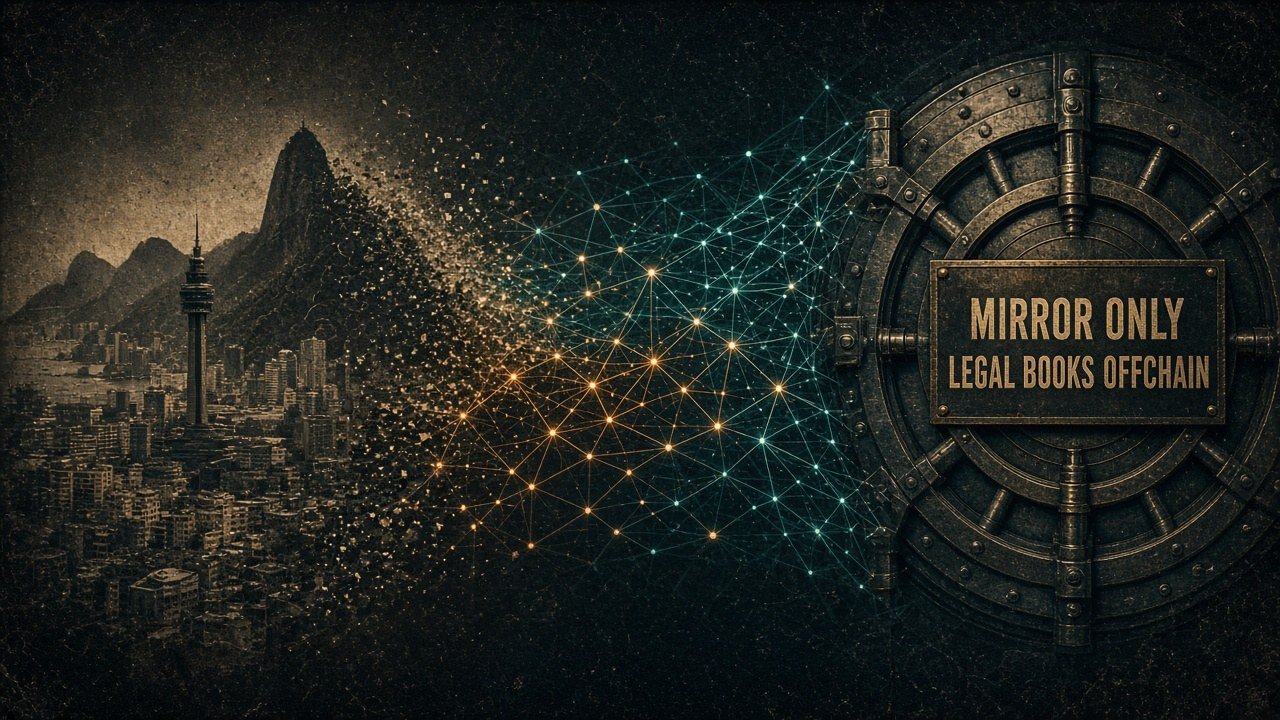
What they are not telling you in the victory-lap headlines: CSD BR’s own systems remain the official source of record for registration, deposit, and settlement. The chain is a complementary query-and-audit layer so authorized participants can check consistency in near real time. Investors’ legal processes do not flip overnight. Participant responsibilities do not rewrite themselves because a token showed up on a public ledger. Ripple’s own release says the model sits inside the current regulatory framework — no change to legal duties, no new approvals required for this phase.
CoinDesk and others will correctly note that CSD BR oversees on the order of BRL 22 trillion in registered assets — roughly $4 trillion. That is the size of the operator, not the size of what just landed on XRPL. Speculation, labeled: every cycle needs a round number. “$4T onchain” is the lazy cousin of this announcement. Hardwire’s rule: mirror ≠ migration. Selected fund shares get a blockchain twin. The depository still keeps the keys to issuance, freezes, and clawbacks when a regulator or court says so. Access for holding and transferring those tokens is permissioned to KYC’d corporate and banking clients in Brazil. Public ledger, gated ownership. That is the actual product.
West’s contrast is the right one for anyone watching institutional rails. Public-chain mirrors inside a regulated CSD are a different bet than bank-led deposit tokens pushed through private coalitions and clearinghouse experiments elsewhere. One path says: keep the legal books where the supervisor already trusts them, bolt on a transparent reconciliation rail, prove it with live fund records, then talk native issuance (CRI, CRA, trading among authorized names). The other path keeps settlement inside club infrastructure and asks the public to take the bank’s word for the token. Different politics of trust. Different who-owns-the-books question.
Republican/populist read: be suspicious of PR that sells decentralization while the clawback button stays with the regulated intermediary — and equally suspicious of legacy banks that want “innovation” without a public audit trail. Brazil just chose the first compromise. Take the live-ops milestone seriously. Do not confuse an audit mirror with legal finality, and do not let a $4 trillion AUM figure become a fake onchain AUM figure.
Sources: Ripple; CoinDesk; CSD BR (via Ripple release)